Of all the things you teach your kids when they’re young, saving money just might be one of the most important. Teaching them to delay gratification could help them avoid unnecessary spending and help them learn to value controlling their money. Here are some tips you can use to educate them about this crucial life skill.
Discuss Wants Versus Needs
Often, when your child says, “I need this” he really means “I want this.” Should you hear this, think of it as an opportunity to help him understand the difference between the two. You might explain that a need includes food, shelter, and clothing, while a want is an extra like candy, video games, or the latest pair of sneakers. You can even quiz children at home by pointing out things and asking them if they are needs or wants. This tool can work wonders.
Allow Your Kids to Earn Money
Whether it’s raking leaves or cleaning the house, chores are one of the best ways to teach young ones both the value of work and the value of money – and saving it.
Create Savings Goals
Telling kids that saving money is important might fall on deaf ears. That’s why helping them decide on a goal to work toward is a great way to demonstrate how saving works. It can be a bike, a phone – anything that they want. Helping them track their money can build motivation to continue their chores, with the pot at the end of the rainbow in sight.
Set Up a Savings Place
For younger kids, a piggy bank or mason jar is perfect. For older kids, a savings account or debit cards are smart ideas. To get a feel for what’s out there, here’s a list of the best high-yield savings accounts. If a debit card works better for you, check out FamZoo, Greenlight, or gohenry. All of these apps will even notify you when a purchase is made!
Offer Incentives
Let’s say your child wants to buy a $400 tablet. Offer to match a percentage of what they’ve saved. Or you can offer a $50 bonus when they reach a milestone number, like $200. When they know this up front, there’ll be no stopping them.
Become Their Creditor
If your kid really, really wants something and is too impatient to wait, lend them the money and charge them interest. This way, they learn a valuable lesson: Saving means delaying gratification for a longer amount of time, but if you wait, the item you want to buy will end up costing less.
Let Them Make Mistakes
Putting your kids in charge of their money allows them to make mistakes and learn from them. While you might want to take control and prevent a costly mistake, it might be better to use the error as a teachable moment.
The takeaway from all these saving tips is teaching kids to live within their means. In our day and age, when prices keep going up, it’s one of the best gifts you can give them.
Sources
10 Tips to Teach Your Child to Save Money
7 Ways to Teach Your Kids to Save
April 1, 2025 · Blog, Tip of the Month, Uncategorized
⏱ 3 min read
Of all the things you teach your kids when they’re young, saving money just might be one of the most important. Teaching them to delay gratification could help them avoid unnecessary spending and help them learn to value controlling their money. Here are some tips you can use to educate them about this crucial life skill.
Discuss Wants Versus Needs
Often, when your child says, “I need this” he really means “I want this.” Should you hear this, think of it as an opportunity to help him understand the difference between the two. You might explain that a need includes food, shelter, and clothing, while a want is an extra like candy, video games, or the latest pair of sneakers. You can even quiz children at home by pointing out things and asking them if they are needs or wants. This tool can work wonders.
Allow Your Kids to Earn Money
Whether it’s raking leaves or cleaning the house, chores are one of the best ways to teach young ones both the value of work and the value of money – and saving it.
Create Savings Goals
Telling kids that saving money is important might fall on deaf ears. That’s why helping them decide on a goal to work toward is a great way to demonstrate how saving works. It can be a bike, a phone – anything that they want. Helping them track their money can build motivation to continue their chores, with the pot at the end of the rainbow in sight.
Set Up a Savings Place
For younger kids, a piggy bank or mason jar is perfect. For older kids, a savings account or debit cards are smart ideas. To get a feel for what’s out there, here’s a list of the best high-yield savings accounts. If a debit card works better for you, check out FamZoo, Greenlight, or gohenry. All of these apps will even notify you when a purchase is made!
Offer Incentives
Let’s say your child wants to buy a $400 tablet. Offer to match a percentage of what they’ve saved. Or you can offer a $50 bonus when they reach a milestone number, like $200. When they know this up front, there’ll be no stopping them.
Become Their Creditor
If your kid really, really wants something and is too impatient to wait, lend them the money and charge them interest. This way, they learn a valuable lesson: Saving means delaying gratification for a longer amount of time, but if you wait, the item you want to buy will end up costing less.
Let Them Make Mistakes
Putting your kids in charge of their money allows them to make mistakes and learn from them. While you might want to take control and prevent a costly mistake, it might be better to use the error as a teachable moment.
The takeaway from all these saving tips is teaching kids to live within their means. In our day and age, when prices keep going up, it’s one of the best gifts you can give them.
Sources
10 Tips to Teach Your Child to Save Money
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
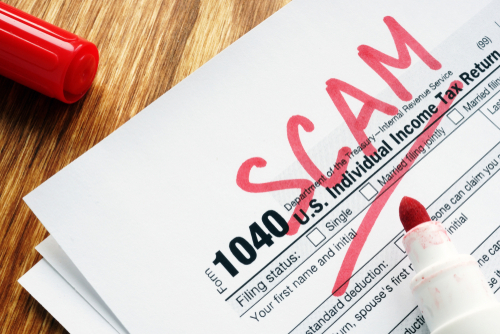
As tax filing season begins, scammers are ramping up efforts to steal taxpayers’ personal information through increasingly sophisticated schemes. Below, we discuss the latest scam, what to look out for in general, and what to do if you suspect something malicious.
New Scam of the Season
The U.S. Treasury Inspector General for Tax Administration (TIGTA) recently issued an alert about a prevalent scam involving Economic Impact Payments.
In this scheme, taxpayers receive texts claiming they’re eligible for a $1,400 Economic Impact Payment, requesting personal information and bank details for deposit. While the IRS is indeed processing some legitimate Recovery Rebate Credit payments from 2021 tax returns, they will never request personal information via text or social media. These legitimate payments will be automatically distributed by late January 2025, either through direct deposit or paper check, with official notification letters sent separately.
Detecting Scam in General
The cybersecurity firm Guardio reports a 77 percent increase in IRS-related spam messages, highlighting how scammers exploit taxpayers’ fears of making mistakes on their returns. Common manipulation tactics include urgent messages claiming:
Tax return errors requiring immediate action to avoid penalties
Account flags demanding immediate information verification to prevent legal action
These fraudulent messages typically contain malicious links designed to steal sensitive information like Social Security numbers, banking details, and payment credentials. They often masquerade as official IRS forms or legitimate tax advisory companies.
Key Warning Signs of Tax Scams:
Requests for sensitive personal or financial information
Links to suspicious websites (legitimate government sites end in .gov)
Misspellings, grammatical errors, or inconsistent formatting
Fuzzy or distorted official logos
Initial contact via email, phone, text, or social media instead of postal mail
What to Do if You Receive a Suspicious Message
If you receive a suspicious message, don’t engage with it. Never click links or provide personal information to unknown sources. Report potential fraud by forwarding the message to phishing@irs.gov or filing a report with TIGTA. If you’re uncertain about correspondence claiming to be from the IRS, verify it by calling 800-829-1040 or visiting IRS.gov. Your online IRS account will display any official notices mailed to you.
If you’ve accidentally engaged with a scam:
Immediately close any suspicious website tabs
Change passwords for potentially compromised accounts
Contact your bank or credit card provider to monitor for fraudulent activity
Report the incident to the IRS and file an identity theft report with the Federal Trade Commission
Consider notifying local law enforcement
When searching for tax-related information online, only use official sources like IRS.gov or the official IRS app. Be wary of sponsored ads and search results that might lead to fraudulent websites. Consider bookmarking official sites for quick, secure access.
Conclusion
Remember, the IRS will never initiate contact through email, text, or social media. When in doubt, assume it’s a scam and verify through official channels. Keeping your personal information secure requires constant vigilance, especially during tax season when scammers are most active.
As Tax Season Opens, We Must Stay Alert to Rising Scam Threats
April 1, 2025 · Blog, Guest Post of the Month, Tax and Financial News, Uncategorized
⏱ 3 min read
As tax filing season begins, scammers are ramping up efforts to steal taxpayers’ personal information through increasingly sophisticated schemes. Below, we discuss the latest scam, what to look out for in general, and what to do if you suspect something malicious.
New Scam of the Season
The U.S. Treasury Inspector General for Tax Administration (TIGTA) recently issued an alert about a prevalent scam involving Economic Impact Payments.
In this scheme, taxpayers receive texts claiming they’re eligible for a $1,400 Economic Impact Payment, requesting personal information and bank details for deposit. While the IRS is indeed processing some legitimate Recovery Rebate Credit payments from 2021 tax returns, they will never request personal information via text or social media. These legitimate payments will be automatically distributed by late January 2025, either through direct deposit or paper check, with official notification letters sent separately.
Detecting Scam in General
The cybersecurity firm Guardio reports a 77 percent increase in IRS-related spam messages, highlighting how scammers exploit taxpayers’ fears of making mistakes on their returns. Common manipulation tactics include urgent messages claiming:
Tax return errors requiring immediate action to avoid penalties
Account flags demanding immediate information verification to prevent legal action
These fraudulent messages typically contain malicious links designed to steal sensitive information like Social Security numbers, banking details, and payment credentials. They often masquerade as official IRS forms or legitimate tax advisory companies.
Key Warning Signs of Tax Scams:
Requests for sensitive personal or financial information
Links to suspicious websites (legitimate government sites end in .gov)
Misspellings, grammatical errors, or inconsistent formatting
Fuzzy or distorted official logos
Initial contact via email, phone, text, or social media instead of postal mail
What to Do if You Receive a Suspicious Message
If you receive a suspicious message, don’t engage with it. Never click links or provide personal information to unknown sources. Report potential fraud by forwarding the message to phishing@irs.gov or filing a report with TIGTA. If you’re uncertain about correspondence claiming to be from the IRS, verify it by calling 800-829-1040 or visiting IRS.gov. Your online IRS account will display any official notices mailed to you.
If you’ve accidentally engaged with a scam:
Immediately close any suspicious website tabs
Change passwords for potentially compromised accounts
Contact your bank or credit card provider to monitor for fraudulent activity
Report the incident to the IRS and file an identity theft report with the Federal Trade Commission
Consider notifying local law enforcement
When searching for tax-related information online, only use official sources like IRS.gov or the official IRS app. Be wary of sponsored ads and search results that might lead to fraudulent websites. Consider bookmarking official sites for quick, secure access.
Conclusion
Remember, the IRS will never initiate contact through email, text, or social media. When in doubt, assume it’s a scam and verify through official channels. Keeping your personal information secure requires constant vigilance, especially during tax season when scammers are most active.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
When you collect a settlement for a lawsuit, you’ll likely also receive a Form 1099 from the IRS. This form serves as a reminder to pay taxes on your settlement; copies are sent to both you and the IRS. These forms match reported income for income tax purposes, making them critical for accurate tax filing.
In lawsuit contexts, two common forms 1099 are issued:
Form 1099-MISC: This version can include various types of settlement payments, often termed other income
Form 1099-NEC: Used specifically for non-employee compensation
Understanding the Difference Between Forms
The distinction between these forms is significant. A Form 1099-NEC informs the IRS that taxes for self-employment should be collected in addition to income taxes. This form is appropriate if you were a non-employee contractor suing for unpaid compensation.
However, in cases like wrongful termination or emotional distress claims, you’ll want the non-wage portion reported on Form 1099-MISC instead of Form 1099-NEC to avoid unnecessary self-employment taxes. Pay close attention because filing an incorrect form can be difficult to correct later.
Double Reporting: When 100% Becomes 200%
A surprising aspect of legal settlement tax reporting is that defendants often issue forms 1099 totaling 200% of the actual settlement amount.
The plaintiff receives a 1099 for 100% of the settlement
The plaintiff’s attorney receives a 1099 for 100% of the settlement
This duplicate reporting occurs because the IRS requires defendants to report the full settlement amount to both parties when payments are made jointly or through the attorney’s trust account. This is done because the defendant may not be aware of how the money is ultimately divided between client and attorney.
Legal Fees and Tax Treatment
The U.S. Supreme Court decided in the case Commissioner v. Banks that gross income for a plaintiff typically includes the part of the settlement paid to their attorney as legal fees. This means you might be taxed on money you never actually received.
To address this issue, plaintiffs should understand when they can deduct legal fees:
Plaintiffs in employment cases, civil rights cases, and most whistleblower cases qualify for deductions
Legal fees must typically be paid in the same year as the settlement (as in contingent fee arrangements)
Outside these case types, deducting legal fees becomes much more difficult
Even in personal physical injury cases, complications arise if punitive damages or interest are awarded
Tax Planning Before Settlement
It’s best to deal with tax reporting before finalizing your settlement agreement. Consider these strategies:
Include specific provisions about which forms 1099 are to be issued
Specify the recipients, amounts, and even which boxes should be completed on the forms
For physical injury cases that should be tax-free, get written commitments about tax reporting
Consider separate checks to lawyer and client when appropriate (though this may not fully prevent attribution of legal fees to plaintiffs)
Without express provisions in your settlement agreement regarding tax forms, correcting any errors later becomes extremely difficult.
Tax-Free Settlements
Some settlements can be totally free of taxation, such as cases where compensation is granted as damages for physical injury. In typical injury cases like auto accidents, damages should be tax-free, but only if there are no punitive damages and no interest as part of the settlement.
Even when you believe your settlement qualifies as tax-free, securing written confirmation about tax reporting in your settlement agreement provides important protection.
Conclusion
Understanding the tax implications of your lawsuit settlement before signing an agreement can save significant headaches and potentially reduce your tax burden. Consulting with a tax professional who specializes in legal settlements is advisable for complex cases.
Understanding IRS Forms 1099 for Lawsuit Settlements
April 1, 2025 · Blog, Tax and Financial News, Uncategorized
⏱ 3 min read
The Basics of Tax Reporting in Legal Settlements
When you collect a settlement for a lawsuit, you’ll likely also receive a Form 1099 from the IRS. This form serves as a reminder to pay taxes on your settlement; copies are sent to both you and the IRS. These forms match reported income for income tax purposes, making them critical for accurate tax filing.
In lawsuit contexts, two common forms 1099 are issued:
Form 1099-MISC: This version can include various types of settlement payments, often termed other income
Form 1099-NEC: Used specifically for non-employee compensation
Understanding the Difference Between Forms
The distinction between these forms is significant. A Form 1099-NEC informs the IRS that taxes for self-employment should be collected in addition to income taxes. This form is appropriate if you were a non-employee contractor suing for unpaid compensation.
However, in cases like wrongful termination or emotional distress claims, you’ll want the non-wage portion reported on Form 1099-MISC instead of Form 1099-NEC to avoid unnecessary self-employment taxes. Pay close attention because filing an incorrect form can be difficult to correct later.
Double Reporting: When 100% Becomes 200%
A surprising aspect of legal settlement tax reporting is that defendants often issue forms 1099 totaling 200% of the actual settlement amount.
The plaintiff receives a 1099 for 100% of the settlement
The plaintiff’s attorney receives a 1099 for 100% of the settlement
This duplicate reporting occurs because the IRS requires defendants to report the full settlement amount to both parties when payments are made jointly or through the attorney’s trust account. This is done because the defendant may not be aware of how the money is ultimately divided between client and attorney.
Legal Fees and Tax Treatment
The U.S. Supreme Court decided in the case Commissioner v. Banks that gross income for a plaintiff typically includes the part of the settlement paid to their attorney as legal fees. This means you might be taxed on money you never actually received.
To address this issue, plaintiffs should understand when they can deduct legal fees:
Plaintiffs in employment cases, civil rights cases, and most whistleblower cases qualify for deductions
Legal fees must typically be paid in the same year as the settlement (as in contingent fee arrangements)
Outside these case types, deducting legal fees becomes much more difficult
Even in personal physical injury cases, complications arise if punitive damages or interest are awarded
Tax Planning Before Settlement
It’s best to deal with tax reporting before finalizing your settlement agreement. Consider these strategies:
Include specific provisions about which forms 1099 are to be issued
Specify the recipients, amounts, and even which boxes should be completed on the forms
For physical injury cases that should be tax-free, get written commitments about tax reporting
Consider separate checks to lawyer and client when appropriate (though this may not fully prevent attribution of legal fees to plaintiffs)
Without express provisions in your settlement agreement regarding tax forms, correcting any errors later becomes extremely difficult.
Tax-Free Settlements
Some settlements can be totally free of taxation, such as cases where compensation is granted as damages for physical injury. In typical injury cases like auto accidents, damages should be tax-free, but only if there are no punitive damages and no interest as part of the settlement.
Even when you believe your settlement qualifies as tax-free, securing written confirmation about tax reporting in your settlement agreement provides important protection.
Conclusion
Understanding the tax implications of your lawsuit settlement before signing an agreement can save significant headaches and potentially reduce your tax burden. Consulting with a tax professional who specializes in legal settlements is advisable for complex cases.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
The subscription economy, according to Forbes, is expected to reach $1.5 trillion in revenue for businesses. With the potential likely realized this year, it’s vital to understand how it is tracked – and more importantly, how it’s able to be tracked on a separate basis.
Also known as net dollar retention (NDR), this metric calculates the proportion of recurring revenue kept from present clients, including upsells and churn, during a defined time frame. Net revenue retention (NRR) evaluates a business’s potential to keep and increase sales from their present clients.
It looks at how well a company leverages existing customer relationships to increase sales through add-ons, complimentary services, etc. It focuses on the long-term growth of recurring revenue from these relationships. It’s calculated as follows:
Based on this result, the company is increasing its revenue from existing customers faster than it’s failing to keep revenue from customer churn, an important metric showing growth.
The following factors impact the formula:
Starting MRR is also referred to as the baseline recurring revenue.
Expansion MRR refers to the added sales from newly added clients, upselling, upgrades, and additions to existing customers’ services.
Churn MRR is the sales missed by customers who stopped or lowered their level and type of services with the company.
Defining a Healthy Revenue Retention Rate
Companies that have a score of more than 100 percent show they’re bringing in more revenue from the existing customer base versus what the company is losing from customer churn. If, however, it’s less than 100 percent, customer satisfaction might be lacking, and customers may either be lost or simply not interested in additional services. Since acquiring new customers is more expensive than keeping current ones, it can lead to reflection on how to improve retention rates.
Journal Entry for Recurring Revenue
Assuming there’s a 12-month contract signed for monthly services, the journal entry would be as follows for a $1,000/monthly payment for a total of $12,000.
Debit
Credit
Cash
$12,000
Unearned Recurring Subscription Income
$12,000
Once the $1,000 subscription income has been earned, the following journal entry would be entered.
Debit
Credit
Unearned Recurring Subscription Income
$1,000
Earned Recurring Subscription Income
$1,000
While each industry and business are different, using this metric can help companies determine if there’s a customer retention problem; then they can start the investigation on how to increase retention for the future.
March 1, 2025 · Blog, General Business News, Uncategorized
⏱ 3 min read
The subscription economy, according to Forbes, is expected to reach $1.5 trillion in revenue for businesses. With the potential likely realized this year, it’s vital to understand how it is tracked – and more importantly, how it’s able to be tracked on a separate basis.
Also known as net dollar retention (NDR), this metric calculates the proportion of recurring revenue kept from present clients, including upsells and churn, during a defined time frame. Net revenue retention (NRR) evaluates a business’s potential to keep and increase sales from their present clients.
It looks at how well a company leverages existing customer relationships to increase sales through add-ons, complimentary services, etc. It focuses on the long-term growth of recurring revenue from these relationships. It’s calculated as follows:
Based on this result, the company is increasing its revenue from existing customers faster than it’s failing to keep revenue from customer churn, an important metric showing growth.
The following factors impact the formula:
Starting MRR is also referred to as the baseline recurring revenue.
Expansion MRR refers to the added sales from newly added clients, upselling, upgrades, and additions to existing customers’ services.
Churn MRR is the sales missed by customers who stopped or lowered their level and type of services with the company.
Defining a Healthy Revenue Retention Rate
Companies that have a score of more than 100 percent show they’re bringing in more revenue from the existing customer base versus what the company is losing from customer churn. If, however, it’s less than 100 percent, customer satisfaction might be lacking, and customers may either be lost or simply not interested in additional services. Since acquiring new customers is more expensive than keeping current ones, it can lead to reflection on how to improve retention rates.
Journal Entry for Recurring Revenue
Assuming there’s a 12-month contract signed for monthly services, the journal entry would be as follows for a $1,000/monthly payment for a total of $12,000.
Debit
Credit
Cash
$12,000
Unearned Recurring Subscription Income
$12,000
Once the $1,000 subscription income has been earned, the following journal entry would be entered.
Debit
Credit
Unearned Recurring Subscription Income
$1,000
Earned Recurring Subscription Income
$1,000
While each industry and business are different, using this metric can help companies determine if there’s a customer retention problem; then they can start the investigation on how to increase retention for the future.
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Artificial intelligence (AI) tools are reshaping content creation. It is now easier for businesses to produce images and videos for use on websites, social media, and other digital outlets. All this is possible without the traditional hurdles of expensive photoshoots, special design skills, or complex video production. However, as exciting as it is, business owners must pose and confront the question of whether these AI-generated images and videos are legally safe for commercial use from a copyright perspective.
Understanding AI-Generated Content and Copyright
AI-generated content is created by training algorithms with massive datasets of existing images, videos, and text. The AI models then analyze patterns from the training data to generate new content. However, issues arise concerning the ownership of the generated content. Without clear legal guidelines, the ownership of AI-generated images and videos remains a gray area that leaves businesses and individuals vulnerable to potential disputes.
Most jurisdictions, including the United States and the EU, deny copyright protection to work purely generated by AI as it lacks human authorship. The U.S. Copyright Office stated that only content with human creative input can be eligible for protection. In its January 2025 report, the U.S. Copyright Office also states that copyrightability must be assessed on a case-by-case basis.
Laws differ globally. For instance, while the U.S. copyright office has rejected applications for AI-generated content, the U.K. allows copyright when a significant human intellectual effort guides the output.
Copyright laws do agree that a business risks infringement claims if AI-generated content resembles existing copyrighted material. So far, there has been a surge in the number of copyright lawsuits because of generative AI. A good example is Getty Images sued Stability AI, alleging its Stable Diffusion model copied millions of Getty’s photos without permission.
Generally, despite the efforts made to develop copyright laws for AI output, unlike content created by humans, there still lacks a clear legal framework for ownership and usage rights. For one, laws and legal frameworks struggle to keep up with the speed at which AI technology advances. This means that currently, no definitive, globally recognized legal standards firmly establish the copyright status of AI creations. For a business, although using AI visuals is not inherently legal or forbidden, it is best to be cautious and take due diligence.
Best Practices Every Business Owner Must Keep in Mind
Read the terms of service (TOS) Every AI image and video generator has its own unique terms of service. Therefore, it is crucial to examine these terms carefully. Specifically, look for clauses that address issues such as commercial usage, ownership, indemnification, and TOS change policies.
Understand model releases This especially applies where the AI-generated images may include recognizable human faces. In the same way that there are rights of publicity and privacy in traditional photography of human models, consider if this also applies to AI-generated faces.
Documentation It is crucial to keep a record of each generated AI visual asset. Keep information such as AI platform used, prompts used, date of creation, TOS at the time of creation, and modifications made to the generated visual.
Consider using well-established platforms. Although there is no AI platform that offers a 100 percent guarantee of copyright safety, it is safer to lean toward well-established and respected AI generators. Also, platforms trained using licensed or public domain data should be considered.
Adopt the “human-in-the-loop” approach. This involves edits such as text overlays, color adjustments, or storyboarding. AI-generated content can be used as a starting point or for inspiration, but it is modified and refined by human designers. This results in a blend of AI assistant and human creative input to potentially mitigate copyright concerns.
Seek expert legal counsel. When dealing with content that is central to a business identity, such as branding or major marketing campaigns, it is critical to seek guidance from an attorney specializing in intellectual property law.
Stay informed Copyright law in the age of AI is not static; it is actively evolving. It is important, therefore, to commit to staying informed about legal developments, court rulings, and evolving practices. Business content strategies and practices also should be adjusted as the legal landscape changes.
Embrace the Future of Visuals Responsibly and Legally
The transformative power of AI to generate stunning visuals is promising to revolutionize business marketing and communication. However, business owners must approach this technology with a balanced perspective. That is, embracing its potential while avoiding copyright infringement, ensuring ethical content creation, and effectively safeguarding intellectual property assets.
Copyright and AI-Generated Images and Videos:
March 1, 2025 · Blog, Uncategorized, What's New in Technology
⏱ 4 min read
What Businesses Need to Know to Stay Legal
Artificial intelligence (AI) tools are reshaping content creation. It is now easier for businesses to produce images and videos for use on websites, social media, and other digital outlets. All this is possible without the traditional hurdles of expensive photoshoots, special design skills, or complex video production. However, as exciting as it is, business owners must pose and confront the question of whether these AI-generated images and videos are legally safe for commercial use from a copyright perspective.
Understanding AI-Generated Content and Copyright
AI-generated content is created by training algorithms with massive datasets of existing images, videos, and text. The AI models then analyze patterns from the training data to generate new content. However, issues arise concerning the ownership of the generated content. Without clear legal guidelines, the ownership of AI-generated images and videos remains a gray area that leaves businesses and individuals vulnerable to potential disputes.
Most jurisdictions, including the United States and the EU, deny copyright protection to work purely generated by AI as it lacks human authorship. The U.S. Copyright Office stated that only content with human creative input can be eligible for protection. In its January 2025 report, the U.S. Copyright Office also states that copyrightability must be assessed on a case-by-case basis.
Laws differ globally. For instance, while the U.S. copyright office has rejected applications for AI-generated content, the U.K. allows copyright when a significant human intellectual effort guides the output.
Copyright laws do agree that a business risks infringement claims if AI-generated content resembles existing copyrighted material. So far, there has been a surge in the number of copyright lawsuits because of generative AI. A good example is Getty Images sued Stability AI, alleging its Stable Diffusion model copied millions of Getty’s photos without permission.
Generally, despite the efforts made to develop copyright laws for AI output, unlike content created by humans, there still lacks a clear legal framework for ownership and usage rights. For one, laws and legal frameworks struggle to keep up with the speed at which AI technology advances. This means that currently, no definitive, globally recognized legal standards firmly establish the copyright status of AI creations. For a business, although using AI visuals is not inherently legal or forbidden, it is best to be cautious and take due diligence.
Best Practices Every Business Owner Must Keep in Mind
Read the terms of service (TOS) Every AI image and video generator has its own unique terms of service. Therefore, it is crucial to examine these terms carefully. Specifically, look for clauses that address issues such as commercial usage, ownership, indemnification, and TOS change policies.
Understand model releases This especially applies where the AI-generated images may include recognizable human faces. In the same way that there are rights of publicity and privacy in traditional photography of human models, consider if this also applies to AI-generated faces.
Documentation It is crucial to keep a record of each generated AI visual asset. Keep information such as AI platform used, prompts used, date of creation, TOS at the time of creation, and modifications made to the generated visual.
Consider using well-established platforms. Although there is no AI platform that offers a 100 percent guarantee of copyright safety, it is safer to lean toward well-established and respected AI generators. Also, platforms trained using licensed or public domain data should be considered.
Adopt the “human-in-the-loop” approach. This involves edits such as text overlays, color adjustments, or storyboarding. AI-generated content can be used as a starting point or for inspiration, but it is modified and refined by human designers. This results in a blend of AI assistant and human creative input to potentially mitigate copyright concerns.
Seek expert legal counsel. When dealing with content that is central to a business identity, such as branding or major marketing campaigns, it is critical to seek guidance from an attorney specializing in intellectual property law.
Stay informed Copyright law in the age of AI is not static; it is actively evolving. It is important, therefore, to commit to staying informed about legal developments, court rulings, and evolving practices. Business content strategies and practices also should be adjusted as the legal landscape changes.
Embrace the Future of Visuals Responsibly and Legally
The transformative power of AI to generate stunning visuals is promising to revolutionize business marketing and communication. However, business owners must approach this technology with a balanced perspective. That is, embracing its potential while avoiding copyright infringement, ensuring ethical content creation, and effectively safeguarding intellectual property assets.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
 Of all the things you teach your kids when they’re young, saving money just might be one of the most important. Teaching them to delay gratification could help them avoid unnecessary spending and help them learn to value controlling their money. Here are some tips you can use to educate them about this crucial life skill.



 As tax filing season begins, scammers are ramping up efforts to steal taxpayers’ personal information through increasingly sophisticated schemes. Below, we discuss the latest scam, what to look out for in general, and what to do if you suspect something malicious.
 The Basics of Tax Reporting in Legal Settlements
 The subscription economy, according to Forbes, is expected to reach $1.5 trillion in revenue for businesses. With the potential likely realized this year, it’s vital to understand how it is tracked – and more importantly, how it’s able to be tracked on a separate basis.