With the global bond market size bigger than many of the world’s biggest economies, it’s important for businesses that sell bonds to understand how to report transactions properly. According to the International Capital Market Association (ICMA), the global bond market’s capitalization is more than $128 trillion.
Defining Bonds
Offered by government or corporate entities, bonds are a static commitment issued to investors. Entities earn money from investors to invest in infrastructure or support operations. Investors receive a coupon payment periodically, and the bond is settled at a future date, which is referred to as the maturity date.
When bonds are tendered, they may be done at a discount, at face value, or at a premium. The valuation relies on the gap at issuance between a bond’s coupon rate and the bond’s yield based on prevailing prices. Upon bond issuance, the bond’s face value is recorded under bonds payable, as the issuing entity receives payment for the bond’s prevailing market value. If there’s a positive difference, it’s recorded at a premium. If there’s a negative difference, it’s recorded at a discount.
Bond Issuance and Accounting Considerations
When sold at par value, after the corporation or government entity receives payment from investors, the issuing entity records it as a liability because it’s liable for the investor’s investment. This would be set up as:
Debit
Credit
Cash
$100
Bonds Payable
$100
Bonds Payable Defined
Since the entity owes the investor, bonds payable is recorded on the liability section of a business’ balance sheet. Much of the time, bonds payable are reported as non-current liabilities.
When sold at a discount, a gap exists between a bond’s par value and the monetary investment the issuing entity obtains from the investor; the issuing entity must record the transaction as a discount on bonds payable account. The journal entry is as follows:
Debit
Credit
Cash
$100
Discount on Bonds Payable
$100
$100
Bonds Payable
$100
If bonds are purchased at a premium, which is when investors pay more for a bond with a higher interest rate, providing higher coupon payments, entities must record it as a premium on bonds payable (POBP) account. It often occurs when purchasers agree to lesser earnings due to the bond having a higher rate than prevailing rates. In the case of a bond’s issuance at a premium, it can be recorded as follows:
Debit
Credit
Cash
$100
POBP
$100
Bonds Payable
$100
If there’s a discount on bonds payable, the recurrent record must reflect the interest expense with a debit transaction and the bonds payable entry must see a credit. This accounting method impacts the bond issuer by growing the total interest expense, which the issuer records.
If, however, the issuer receives payment from investors beyond the face value, the interest expense must be credited, and the premium on bonds payable entry should receive a debit.
Conclusion
Whether it’s a business issuing bonds or an investor evaluating a company, understanding how to account for bonds is essential to evaluate a business’ financial health.
How to Account for Bonds
October 1, 2026 · Accounting News, Blog, Uncategorized
⏱ 3 min read
With the global bond market size bigger than many of the world’s biggest economies, it’s important for businesses that sell bonds to understand how to report transactions properly. According to the International Capital Market Association (ICMA), the global bond market’s capitalization is more than $128 trillion.
Defining Bonds
Offered by government or corporate entities, bonds are a static commitment issued to investors. Entities earn money from investors to invest in infrastructure or support operations. Investors receive a coupon payment periodically, and the bond is settled at a future date, which is referred to as the maturity date.
When bonds are tendered, they may be done at a discount, at face value, or at a premium. The valuation relies on the gap at issuance between a bond’s coupon rate and the bond’s yield based on prevailing prices. Upon bond issuance, the bond’s face value is recorded under bonds payable, as the issuing entity receives payment for the bond’s prevailing market value. If there’s a positive difference, it’s recorded at a premium. If there’s a negative difference, it’s recorded at a discount.
Bond Issuance and Accounting Considerations
When sold at par value, after the corporation or government entity receives payment from investors, the issuing entity records it as a liability because it’s liable for the investor’s investment. This would be set up as:
Debit
Credit
Cash
$100
Bonds Payable
$100
Bonds Payable Defined
Since the entity owes the investor, bonds payable is recorded on the liability section of a business’ balance sheet. Much of the time, bonds payable are reported as non-current liabilities.
When sold at a discount, a gap exists between a bond’s par value and the monetary investment the issuing entity obtains from the investor; the issuing entity must record the transaction as a discount on bonds payable account. The journal entry is as follows:
Debit
Credit
Cash
$100
Discount on Bonds Payable
$100
$100
Bonds Payable
$100
If bonds are purchased at a premium, which is when investors pay more for a bond with a higher interest rate, providing higher coupon payments, entities must record it as a premium on bonds payable (POBP) account. It often occurs when purchasers agree to lesser earnings due to the bond having a higher rate than prevailing rates. In the case of a bond’s issuance at a premium, it can be recorded as follows:
Debit
Credit
Cash
$100
POBP
$100
Bonds Payable
$100
If there’s a discount on bonds payable, the recurrent record must reflect the interest expense with a debit transaction and the bonds payable entry must see a credit. This accounting method impacts the bond issuer by growing the total interest expense, which the issuer records.
If, however, the issuer receives payment from investors beyond the face value, the interest expense must be credited, and the premium on bonds payable entry should receive a debit.
Conclusion
Whether it’s a business issuing bonds or an investor evaluating a company, understanding how to account for bonds is essential to evaluate a business’ financial health.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Continuing Appropriations and Extensions Act, 2027 (HR 6500) – This appropriations bill was finalized and passed by both the House and the Senate on Sept. 1. The act funds the fiscal year 2027 government budget through Dec. 11 at current levels. It was signed by the President on Sept. 2.
Prison Staff Safety Enhancement Act (S 307) – This bill is designed to address sexual harassment and sexual assault of Bureau of Prisons correctional officers and other staff by incarcerated prisoners. Specifically, it details national standards for the prevention, reduction, and punishment of perpetrators. The legislation was introduced by Sen. Marsha Blackburn (R-TN) on Jan. 29, 2025. It passed in the Senate on April 29, 2025; in the House on Aug. 31; and was enacted by the president on Sept. 16.
Retire through Ownership Act (S 2403) – Introduced by Sen. Roger Marshall (R-KS) on July 23, 2025, this bill amends the Employee Retirement Income Security Act of 1974. ESOPs are Employee Stock Ownership Plans that enable employees to accrue shares of their employers’ stock as part of a pension plan, in which they receive the cash value of their shares upon retirement. This bill clearly defines how a good-faith valuation should be determined by independent professional appraisers, based on IRS Revenue Ruling 59-60 for valuing privately held stock. In the past, ambiguous valuation methods have resulted in litigation. This act passed in the Senate on October 9, 2025, and in the House on Sept. 16. It currently awaits the president’s signature.
Lindsey O. Graham Sanctioning Russia and Iran Act of 2026 (HR 5334) – This largely bipartisan act was championed by the late Sen. Lindsey Graham (R-SC). The legislation imposes a variety of sanctions, tariffs, and prohibitions related to Russia and Iran, and explicitly prohibits U.S. persons from making new investments in Russia. It also expands the tax deduction for early childhood education teachers for classroom expenses. The bill was introduced on Sept. 11, 2025, by Rep. Jimmy Panetta (D-CA). It passed in the House on April 27 and in the Senate on Aug. 7, with final changes agreed upon on Sept. 16. The president signed the bill into law a day later.
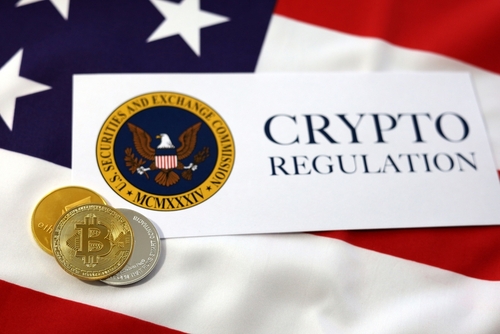
Digital Asset Market Clarity Act (HR 3633) – Known as the Clarity Act, the purpose of this Trump Administration-backed bill is to implement the first regulations for the crypto sector. The bill was introduced by Rep. French Hill (R-AR) on May 29, 2025. It passed in the House on July 17, 2025. However, opponents of the bill say the industry-led standards are far too lenient and do not provide enough safeguards. The bill recently failed in the Senate after a party-line cloture vote, which means the debate ended before the floor could vote on the bill (considered a filibuster). The cloture vote does not rule out the Senate trying again at a later date.
Ratepayer Protection Act (HR 9340) – In an effort to rein in AI data center utility costs, this bill would require state utilities to consider adopting standards to ensure cost recovery for the generation, transmission, and distribution services of large-load electricity customers. This high-stakes, bipartisan issue comes ahead of the midterm elections in an effort to assure voters that local data centers will not ramp up local residents’ utility bills. The legislation was introduced by Rep. Gabe Evans (R-CO) on June 18. It passed in the House on Sept. 16 and currently resides in the Senate.
Stopping Political Discrimination in Disaster Assistance Act (HR 1342) – Current law states that federal major disaster emergency relief and assistance must be provided without discrimination on the basis of race, color, religion, nationality, sex, age, disability, English proficiency or economic status. The bill, introduced by Rep. Scott Perry (R-PA) on Feb. 13, 2025, would add political affiliation protection under this requirement. The act passed in the House on Sept. 16 and awaits consideration in the Senate.
Pre-Election Focus on Russian/Iran Sanctions, AI Utility Bills, Crypto Regulation and Nondiscriminatory FEMA Assistance
October 1, 2026 · Blog, Congress at Work, Uncategorized
⏱ 4 min read
Continuing Appropriations and Extensions Act, 2027 (HR 6500) – This appropriations bill was finalized and passed by both the House and the Senate on Sept. 1. The act funds the fiscal year 2027 government budget through Dec. 11 at current levels. It was signed by the President on Sept. 2.
Prison Staff Safety Enhancement Act (S 307) – This bill is designed to address sexual harassment and sexual assault of Bureau of Prisons correctional officers and other staff by incarcerated prisoners. Specifically, it details national standards for the prevention, reduction, and punishment of perpetrators. The legislation was introduced by Sen. Marsha Blackburn (R-TN) on Jan. 29, 2025. It passed in the Senate on April 29, 2025; in the House on Aug. 31; and was enacted by the president on Sept. 16.
Retire through Ownership Act (S 2403) – Introduced by Sen. Roger Marshall (R-KS) on July 23, 2025, this bill amends the Employee Retirement Income Security Act of 1974. ESOPs are Employee Stock Ownership Plans that enable employees to accrue shares of their employers’ stock as part of a pension plan, in which they receive the cash value of their shares upon retirement. This bill clearly defines how a good-faith valuation should be determined by independent professional appraisers, based on IRS Revenue Ruling 59-60 for valuing privately held stock. In the past, ambiguous valuation methods have resulted in litigation. This act passed in the Senate on October 9, 2025, and in the House on Sept. 16. It currently awaits the president’s signature.
Lindsey O. Graham Sanctioning Russia and Iran Act of 2026 (HR 5334) – This largely bipartisan act was championed by the late Sen. Lindsey Graham (R-SC). The legislation imposes a variety of sanctions, tariffs, and prohibitions related to Russia and Iran, and explicitly prohibits U.S. persons from making new investments in Russia. It also expands the tax deduction for early childhood education teachers for classroom expenses. The bill was introduced on Sept. 11, 2025, by Rep. Jimmy Panetta (D-CA). It passed in the House on April 27 and in the Senate on Aug. 7, with final changes agreed upon on Sept. 16. The president signed the bill into law a day later.
Digital Asset Market Clarity Act (HR 3633) – Known as the Clarity Act, the purpose of this Trump Administration-backed bill is to implement the first regulations for the crypto sector. The bill was introduced by Rep. French Hill (R-AR) on May 29, 2025. It passed in the House on July 17, 2025. However, opponents of the bill say the industry-led standards are far too lenient and do not provide enough safeguards. The bill recently failed in the Senate after a party-line cloture vote, which means the debate ended before the floor could vote on the bill (considered a filibuster). The cloture vote does not rule out the Senate trying again at a later date.
Ratepayer Protection Act (HR 9340) – In an effort to rein in AI data center utility costs, this bill would require state utilities to consider adopting standards to ensure cost recovery for the generation, transmission, and distribution services of large-load electricity customers. This high-stakes, bipartisan issue comes ahead of the midterm elections in an effort to assure voters that local data centers will not ramp up local residents’ utility bills. The legislation was introduced by Rep. Gabe Evans (R-CO) on June 18. It passed in the House on Sept. 16 and currently resides in the Senate.
Stopping Political Discrimination in Disaster Assistance Act (HR 1342) – Current law states that federal major disaster emergency relief and assistance must be provided without discrimination on the basis of race, color, religion, nationality, sex, age, disability, English proficiency or economic status. The bill, introduced by Rep. Scott Perry (R-PA) on Feb. 13, 2025, would add political affiliation protection under this requirement. The act passed in the House on Sept. 16 and awaits consideration in the Senate.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
For years, corporate fraud was limited by the costs, expertise, and resources required to carry out a convincing deception. Artificial intelligence (AI) has changed this.
Today, AI can create realistic voices, videos, emails, invoices, identities, and customer interactions at a scale and speed that traditional fraud controls were never designed to address. AI-powered fraud is a governance, financial, and strategic risk – not just an IT problem.
The Evolution of Corporate Fraud
Fraud is no longer limited to static phishing emails. Threat actors, from organized criminal syndicates to rogue insiders, use large language models and advanced machine learning to execute complex, multilayered fraud schemes.
One of the most cited reference cases is the 2024 Arup incident. A finance employee at the engineering firm’s Hong Kong office was tricked into transferring about $25 million across multiple transactions after joining a video conference call with deepfake replicas of the company’s CFO and other colleagues. The fraud succeeded because it targeted the human authorization step, the exact step where financial controls assume identity can be trusted on sight and sound.
Beyond deepfake executives, new trends include synthetic vendor creation, where generative models fabricate entire corporate entities. Each comes complete with tax IDs, websites, regulatory filings, and executive profiles. They are used to infiltrate accounts payable systems. Bad actors also use machine learning to reverse-engineer enterprise anti-fraud algorithms, find blind spots, and execute micro-transactions that stay beneath detection thresholds.
Why the Numbers Should Worry Boards, Not Just Security Teams
The 2026 INTERPOL Global Financial Fraud Threat Assessment flagged AI-powered fraud as one of organized crime’s primary growth sectors. It reports that fraud alerts have risen 54 percent since 2024, with more than 1,500 cross-border cases involving $1.1 billion in lost assets.
The Regulatory Gap Executives Should Worry About
Regulation is accelerating, but it is not solving the fraud problem. The EU AI Act’s transparency provisions took effect Aug. 2. It requires the disclosure of AI-generated content, with penalties for noncompliance. As of July 2026, 48 states in the United States have enacted at least one deepfake-related law, according to Ballotpedia’s tracker. Yet none of these frameworks is really built for enterprise fraud. They target content moderation, disclosure, and non-consensual media. None directly addresses the authorization workflows attackers actually exploit. A company that is fully compliant with deepfake laws would still be exposed by the Arup scenario.
Regulators such as the Federal Trade Commission (FTC) have signaled that using AI to deceive is prosecutable under existing fraud statutes, but enforcement is reactive and case-by-case. Executives who treat fraud as just a criminal act rather than a governance failure arising from inadequate technical oversight face severe personal and corporate liability.
Strategic Challenges and Recommended Actions
Defending against AI-powered fraud requires rethinking how security spending is justified. Traditional ROI models rely on historical loss avoidance, but in the age of generative fraud, past losses are an unreliable predictor of future exposure.
The primary implementation challenge is friction versus security. Deploying stronger authentication and behavior monitoring across corporate touchpoints creates friction that employees and vendors resist. In addition, integrating AI defenses into legacy enterprise resource planning (ERP) systems creates technical debt. Organizations also struggle with data silos, even though fraud detection now requires real-time visibility across all departments.
To protect enterprise value, leadership teams should move from passive compliance to active resilience.
Verify out of band. Require a callback to a known number and dual approval for large or unusual transfers. Never authorize a payment on a voice or video request alone.
Strengthen authentication. Use multifactor cryptographic verification and zero-trust principles (verify every request, regardless of source). Treat biometrics with caution, since deepfakes can spoof them.
Red-team for AI fraud. Have ethical hackers use generative AI to stress test internal systems and give the risk committee ownership of the results.
Use AI to fight AI. Deploy monitoring tools that flag behavioral anomalies across internal communications, ledger entries, and vendor registries in real time.
Establish cross-functional fraud task forces. Break down departmental silos and treat fraud detection as an integrated business process.
Future Outlook
As AI advances, the convergence of generative AI and autonomous software agents suggest that corporate fraud may increasingly be automated, including by self-directed AI agents operating as fraud syndicates. Business leaders must recognize that the future of corporate defense relies not on human vigilance alone, but on building resilient, self-healing digital ecosystems where trust is algorithmically verified and continuously audited.
AI-Powered Corporate Fraud: What Business Leaders Need to Know
October 1, 2026 · Blog, Uncategorized, What's New in Technology
⏱ 4 min read
For years, corporate fraud was limited by the costs, expertise, and resources required to carry out a convincing deception. Artificial intelligence (AI) has changed this.
Today, AI can create realistic voices, videos, emails, invoices, identities, and customer interactions at a scale and speed that traditional fraud controls were never designed to address. AI-powered fraud is a governance, financial, and strategic risk – not just an IT problem.
The Evolution of Corporate Fraud
Fraud is no longer limited to static phishing emails. Threat actors, from organized criminal syndicates to rogue insiders, use large language models and advanced machine learning to execute complex, multilayered fraud schemes.
One of the most cited reference cases is the 2024 Arup incident. A finance employee at the engineering firm’s Hong Kong office was tricked into transferring about $25 million across multiple transactions after joining a video conference call with deepfake replicas of the company’s CFO and other colleagues. The fraud succeeded because it targeted the human authorization step, the exact step where financial controls assume identity can be trusted on sight and sound.
Beyond deepfake executives, new trends include synthetic vendor creation, where generative models fabricate entire corporate entities. Each comes complete with tax IDs, websites, regulatory filings, and executive profiles. They are used to infiltrate accounts payable systems. Bad actors also use machine learning to reverse-engineer enterprise anti-fraud algorithms, find blind spots, and execute micro-transactions that stay beneath detection thresholds.
Why the Numbers Should Worry Boards, Not Just Security Teams
The 2026 INTERPOL Global Financial Fraud Threat Assessment flagged AI-powered fraud as one of organized crime’s primary growth sectors. It reports that fraud alerts have risen 54 percent since 2024, with more than 1,500 cross-border cases involving $1.1 billion in lost assets.
The Regulatory Gap Executives Should Worry About
Regulation is accelerating, but it is not solving the fraud problem. The EU AI Act’s transparency provisions took effect Aug. 2. It requires the disclosure of AI-generated content, with penalties for noncompliance. As of July 2026, 48 states in the United States have enacted at least one deepfake-related law, according to Ballotpedia’s tracker. Yet none of these frameworks is really built for enterprise fraud. They target content moderation, disclosure, and non-consensual media. None directly addresses the authorization workflows attackers actually exploit. A company that is fully compliant with deepfake laws would still be exposed by the Arup scenario.
Regulators such as the Federal Trade Commission (FTC) have signaled that using AI to deceive is prosecutable under existing fraud statutes, but enforcement is reactive and case-by-case. Executives who treat fraud as just a criminal act rather than a governance failure arising from inadequate technical oversight face severe personal and corporate liability.
Strategic Challenges and Recommended Actions
Defending against AI-powered fraud requires rethinking how security spending is justified. Traditional ROI models rely on historical loss avoidance, but in the age of generative fraud, past losses are an unreliable predictor of future exposure.
The primary implementation challenge is friction versus security. Deploying stronger authentication and behavior monitoring across corporate touchpoints creates friction that employees and vendors resist. In addition, integrating AI defenses into legacy enterprise resource planning (ERP) systems creates technical debt. Organizations also struggle with data silos, even though fraud detection now requires real-time visibility across all departments.
To protect enterprise value, leadership teams should move from passive compliance to active resilience.
Verify out of band. Require a callback to a known number and dual approval for large or unusual transfers. Never authorize a payment on a voice or video request alone.
Strengthen authentication. Use multifactor cryptographic verification and zero-trust principles (verify every request, regardless of source). Treat biometrics with caution, since deepfakes can spoof them.
Red-team for AI fraud. Have ethical hackers use generative AI to stress test internal systems and give the risk committee ownership of the results.
Use AI to fight AI. Deploy monitoring tools that flag behavioral anomalies across internal communications, ledger entries, and vendor registries in real time.
Establish cross-functional fraud task forces. Break down departmental silos and treat fraud detection as an integrated business process.
Future Outlook
As AI advances, the convergence of generative AI and autonomous software agents suggest that corporate fraud may increasingly be automated, including by self-directed AI agents operating as fraud syndicates. Business leaders must recognize that the future of corporate defense relies not on human vigilance alone, but on building resilient, self-healing digital ecosystems where trust is algorithmically verified and continuously audited.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Temps are dropping, the leaves are turning, and you know what that means: Fall is here, which is the best time to prepare your house for the chill that follows. But we all know that keeping warm takes energy and, yes, is costly. Here are a few easy ways to conserve.
Fix stuff around your house. These are simple and might require a little elbow grease on your part, but they’re well worth it because they help your house stay warmer, eliminate drafts, and help your heater work more efficiently.
Seal gaps around your windows and doors with caulk or weatherstripping.
Close fireplace dampers when you’re not using them.
Replace HVAC filters. For your furnace, this should be done one to three months before cold weather hits. It helps improve air quality (and air flow) inside your home.
Add door sweeps to exterior doors.
Reverse your ceiling fans; set them to clockwise and put them on a low setting to push the warm air down into the room.
Hang thick(er) curtains so heat doesn’t seep out.
Make sure vents and returns aren’t blocked by furniture or rugs.
Check your heating system. Before the Arctic blast arrives, these tasks are key:
Schedule an HVAC inspection – aka a tune-up.
Install a programmable or smart thermostat.
Lower your thermostat by 7-10 degrees when you’re away.
Look at your insulation. These chores might require you to hire someone.
Add attic insulation if your house is under-insulated so you can reduce your heating costs and keep your house toasty. (In fact, poor insulation is one of the biggest sources of energy loss.)
Insulate pipes that are exposed, as well as your water heater.
Seal and insulate all your ductwork in your attic, garage, and crawl spaces.
Inspect your water heater. Making sure you have warm water in the cooler months is critical. You’ll be quite happy not having to take cold showers, as well as not expending as much energy.
Lower your water heater temperature to 120°F.
Install low-flow showerheads.
Fix dripping faucets immediately.
Examine the exterior of your house. Even the outside of your home needs attention.
Clean gutters and downspouts to prevent ice dams, moisture problems, and foundation issues.
Trim branches that could block winter sunlight from south-facing windows.
Check for cracks where utilities enter the house and seal them.
Check your roof, too, for signs of wear or damage.
Test your heating system early. Put this on your calendar! Don’t wait until it’s a tundra outside to turn on your furnace or heat pump.
If you need repairs, schedule maintenance before HVAC companies get all booked up.
Check your smoke and carbon monoxide detectors. Don’t leave this unattended!
Replace batteries if needed and test them all. You want to make sure your family’s safe during the upcoming heating season.
Even though fall is upon us, know this: Winter is coming, as the show famously claims. You can never be too prepared!
How to Save Energy This Fall
October 1, 2026 · Blog, Tip of the Month, Uncategorized
⏱ 3 min read
Temps are dropping, the leaves are turning, and you know what that means: Fall is here, which is the best time to prepare your house for the chill that follows. But we all know that keeping warm takes energy and, yes, is costly. Here are a few easy ways to conserve.
Fix stuff around your house. These are simple and might require a little elbow grease on your part, but they’re well worth it because they help your house stay warmer, eliminate drafts, and help your heater work more efficiently.
Seal gaps around your windows and doors with caulk or weatherstripping.
Close fireplace dampers when you’re not using them.
Replace HVAC filters. For your furnace, this should be done one to three months before cold weather hits. It helps improve air quality (and air flow) inside your home.
Add door sweeps to exterior doors.
Reverse your ceiling fans; set them to clockwise and put them on a low setting to push the warm air down into the room.
Hang thick(er) curtains so heat doesn’t seep out.
Make sure vents and returns aren’t blocked by furniture or rugs.
Check your heating system. Before the Arctic blast arrives, these tasks are key:
Schedule an HVAC inspection – aka a tune-up.
Install a programmable or smart thermostat.
Lower your thermostat by 7-10 degrees when you’re away.
Look at your insulation. These chores might require you to hire someone.
Add attic insulation if your house is under-insulated so you can reduce your heating costs and keep your house toasty. (In fact, poor insulation is one of the biggest sources of energy loss.)
Insulate pipes that are exposed, as well as your water heater.
Seal and insulate all your ductwork in your attic, garage, and crawl spaces.
Inspect your water heater. Making sure you have warm water in the cooler months is critical. You’ll be quite happy not having to take cold showers, as well as not expending as much energy.
Lower your water heater temperature to 120°F.
Install low-flow showerheads.
Fix dripping faucets immediately.
Examine the exterior of your house. Even the outside of your home needs attention.
Clean gutters and downspouts to prevent ice dams, moisture problems, and foundation issues.
Trim branches that could block winter sunlight from south-facing windows.
Check for cracks where utilities enter the house and seal them.
Check your roof, too, for signs of wear or damage.
Test your heating system early. Put this on your calendar! Don’t wait until it’s a tundra outside to turn on your furnace or heat pump.
If you need repairs, schedule maintenance before HVAC companies get all booked up.
Check your smoke and carbon monoxide detectors. Don’t leave this unattended!
Replace batteries if needed and test them all. You want to make sure your family’s safe during the upcoming heating season.
Even though fall is upon us, know this: Winter is coming, as the show famously claims. You can never be too prepared!
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
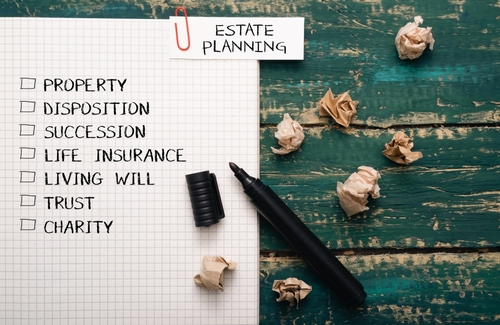
The purpose of estate planning is to distribute your assets to heirs in a formal, legal process. If you do not have any heirs to speak of, you might not feel the need to do this. However, your assets will go somewhere, so you may want to have control over that before the state steps in to decide for you.
Without a formal will, the general rule for inheritance distribution starts with a surviving spouse and children (who often share the estate), followed by grandchildren, parents, siblings, nephews and nieces, grandparents, then other extended relatives such as aunts, uncles and cousins. The exact order varies by state. Note that ex-spouses, and in most states stepchildren, receive nothing under standard state inheritance laws; they must be specified in a will or trust document, or named as an account beneficiary, to receive any consideration.
This means that, without a will or close family heir, your assets could go to an estranged sibling or even a cousin you’ve never met. If you have absolutely no family left when you pass on, the proceeds generally go to the state through a process called escheat (this includes funds from physical assets that are auctioned off).
Start with Living Matters
Before you start allocating where your assets go after your death, first complete paperwork assigning people to manage your assets if you ever become incapacitated while still alive. The key documents include:
Durable Power of Attorney (DPOA) – this document names an agent, such as a trusted friend, attorney, or bank trust department, to take over managing your financial and legal affairs if you are deemed unable.
Health Care Directive – authorizes someone to make medical decisions on your behalf when you are unable.
Living Will – details what life-saving procedures and treatments you would and would not like to receive in order to keep you alive. Separately, a DNR (do not resuscitate) order, signed by your physician, directs medical staff not to perform CPR if your heart or breathing stops.
Choose Your Estate Manager
Your will should assign an executor to manage your estate once you pass away. Again, this can be a friend or a custodian (e.g., bank, attorney, financial advisor). This person is responsible for initiating probate court proceedings and distributing assets as dictated by your will. Responsibilities may include notifying your landlord/lender(s), utility providers, banks, credit card companies, investments, and insurance companies of your passing, as well as managing the sale of any property you own. Most states allow any competent adult to serve as executor, including the attorney who drafted your will, though some states restrict people with felony convictions or those who live out of state.
It behooves the heirless to consider estate planning to better allocate funds toward people or causes they care about, such as friends, coworkers, or charities. For example:
Animal shelter or humane society
Local church or other religious institution
The public library
The Public Broadcasting Service (PBS)
A local land trust, the World Wildlife Fund or other conservation organizations
A favorite city institution, such as a museum, zoo, symphony, ballet or theater
Scholarship fund for your alma mater – K-12 or university
YMCA or Jewish community center
Medical institutions, such as local clinics, St. Jude Children’s Research Hospital, Planned Parenthood, cancer or other disease research
Charities for children, such as the National Center for Missing & Exploited Children or Children’s Health Fund
If nothing local appeals, browse options at websites such as CharityWatch.org, a website dedicated to assessing how efficiently charities use donations.
Note that retirement accounts and life insurance policies generally request a beneficiary, and many bank and brokerage accounts allow one. You may not even remember that when you opened an account years ago, you listed your boyfriend or wife at the time as your beneficiary, even though that person is now your ex. Be aware that these beneficiary designations supersede any will instructions. These assets pass directly to the named beneficiary outside of probate, without going through your executor. Be sure to check and confirm your beneficiary designations while you are still alive to eliminate this issue. Many states automatically revoke an ex-spouse’s designation after a divorce, but that rule generally does not apply to employer retirement plans such as 401(k)s, so an ex could still collect. If no beneficiary is named, the account typically becomes part of your estate and goes through probate.
Charitable Donations
For people with substantial assets who want to leave money to one or more charities, sophisticated philanthropic vehicles include:
Charitable remainder trust – The money is deposited into a trust while you are still alive. You receive an immediate tax deduction based on the present value of the charity’s future share (the remainder interest) of this irrevocable trust, as well as an income stream from the trust for life or for a set term of up to 20 years. When the trust ends, whatever charity you designate receives the remaining assets.
Donor-advised funds – You make an irrevocable, tax-deductible contribution of cash, securities, or appreciated noncash assets to a fund, which is professionally managed for future growth. You may recommend money be granted to a qualified 501(c)(3) charity over time, basically leaving a legacy that continues to give.
Private foundations – You can actually start your own charitable organization with an initial tax-deductible gift and appoint a board of directors or trustees (who may receive reasonable compensation) to manage and distribute assets according to your wishes. Foundations can make grants beyond public charities in limited cases, but only under strict IRS rules. They must also distribute at least 5 percent of their assets each year and pay an excise tax on investment income, and donors face lower deduction limits than for gifts to public charities.
It is best to consult with a financial advisor, tax professional, or estate planning attorney with experience in setting up a sophisticated charitable giving plan to make the most of your contributions.
Heirless Estate Planning
October 1, 2026 · Blog, Financial Planning, Uncategorized
⏱ 6 min read
The purpose of estate planning is to distribute your assets to heirs in a formal, legal process. If you do not have any heirs to speak of, you might not feel the need to do this. However, your assets will go somewhere, so you may want to have control over that before the state steps in to decide for you.
Without a formal will, the general rule for inheritance distribution starts with a surviving spouse and children (who often share the estate), followed by grandchildren, parents, siblings, nephews and nieces, grandparents, then other extended relatives such as aunts, uncles and cousins. The exact order varies by state. Note that ex-spouses, and in most states stepchildren, receive nothing under standard state inheritance laws; they must be specified in a will or trust document, or named as an account beneficiary, to receive any consideration.
This means that, without a will or close family heir, your assets could go to an estranged sibling or even a cousin you’ve never met. If you have absolutely no family left when you pass on, the proceeds generally go to the state through a process called escheat (this includes funds from physical assets that are auctioned off).
Start with Living Matters
Before you start allocating where your assets go after your death, first complete paperwork assigning people to manage your assets if you ever become incapacitated while still alive. The key documents include:
Durable Power of Attorney (DPOA) – this document names an agent, such as a trusted friend, attorney, or bank trust department, to take over managing your financial and legal affairs if you are deemed unable.
Health Care Directive – authorizes someone to make medical decisions on your behalf when you are unable.
Living Will – details what life-saving procedures and treatments you would and would not like to receive in order to keep you alive. Separately, a DNR (do not resuscitate) order, signed by your physician, directs medical staff not to perform CPR if your heart or breathing stops.
Choose Your Estate Manager
Your will should assign an executor to manage your estate once you pass away. Again, this can be a friend or a custodian (e.g., bank, attorney, financial advisor). This person is responsible for initiating probate court proceedings and distributing assets as dictated by your will. Responsibilities may include notifying your landlord/lender(s), utility providers, banks, credit card companies, investments, and insurance companies of your passing, as well as managing the sale of any property you own. Most states allow any competent adult to serve as executor, including the attorney who drafted your will, though some states restrict people with felony convictions or those who live out of state.
It behooves the heirless to consider estate planning to better allocate funds toward people or causes they care about, such as friends, coworkers, or charities. For example:
Animal shelter or humane society
Local church or other religious institution
The public library
The Public Broadcasting Service (PBS)
A local land trust, the World Wildlife Fund or other conservation organizations
A favorite city institution, such as a museum, zoo, symphony, ballet or theater
Scholarship fund for your alma mater – K-12 or university
YMCA or Jewish community center
Medical institutions, such as local clinics, St. Jude Children’s Research Hospital, Planned Parenthood, cancer or other disease research
Charities for children, such as the National Center for Missing & Exploited Children or Children’s Health Fund
If nothing local appeals, browse options at websites such as CharityWatch.org, a website dedicated to assessing how efficiently charities use donations.
Note that retirement accounts and life insurance policies generally request a beneficiary, and many bank and brokerage accounts allow one. You may not even remember that when you opened an account years ago, you listed your boyfriend or wife at the time as your beneficiary, even though that person is now your ex. Be aware that these beneficiary designations supersede any will instructions. These assets pass directly to the named beneficiary outside of probate, without going through your executor. Be sure to check and confirm your beneficiary designations while you are still alive to eliminate this issue. Many states automatically revoke an ex-spouse’s designation after a divorce, but that rule generally does not apply to employer retirement plans such as 401(k)s, so an ex could still collect. If no beneficiary is named, the account typically becomes part of your estate and goes through probate.
Charitable Donations
For people with substantial assets who want to leave money to one or more charities, sophisticated philanthropic vehicles include:
Charitable remainder trust – The money is deposited into a trust while you are still alive. You receive an immediate tax deduction based on the present value of the charity’s future share (the remainder interest) of this irrevocable trust, as well as an income stream from the trust for life or for a set term of up to 20 years. When the trust ends, whatever charity you designate receives the remaining assets.
Donor-advised funds – You make an irrevocable, tax-deductible contribution of cash, securities, or appreciated noncash assets to a fund, which is professionally managed for future growth. You may recommend money be granted to a qualified 501(c)(3) charity over time, basically leaving a legacy that continues to give.
Private foundations – You can actually start your own charitable organization with an initial tax-deductible gift and appoint a board of directors or trustees (who may receive reasonable compensation) to manage and distribute assets according to your wishes. Foundations can make grants beyond public charities in limited cases, but only under strict IRS rules. They must also distribute at least 5 percent of their assets each year and pay an excise tax on investment income, and donors face lower deduction limits than for gifts to public charities.
It is best to consult with a financial advisor, tax professional, or estate planning attorney with experience in setting up a sophisticated charitable giving plan to make the most of your contributions.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
 With the global bond market size bigger than many of the world’s biggest economies, it’s important for businesses that sell bonds to understand how to report transactions properly. According to the International Capital Market Association (ICMA), the global bond market’s capitalization is more than $128 trillion.



 Continuing Appropriations and Extensions Act, 2027 (HR 6500) – This appropriations bill was finalized and passed by both the House and the Senate on Sept. 1. The act funds the fiscal year 2027 government budget through Dec. 11 at current levels. It was signed by the President on Sept. 2.
 For years, corporate fraud was limited by the costs, expertise, and resources required to carry out a convincing deception. Artificial intelligence (AI) has changed this.
 Temps are dropping, the leaves are turning, and you know what that means: Fall is here, which is the best time to prepare your house for the chill that follows. But we all know that keeping warm takes energy and, yes, is costly. Here are a few easy ways to conserve.
 The purpose of estate planning is to distribute your assets to heirs in a formal, legal process. If you do not have any heirs to speak of, you might not feel the need to do this. However, your assets will go somewhere, so you may want to have control over that before the state steps in to decide for you.