United States-Taiwan Initiative on 21st-Century Trade First Agreement Implementation Act (HR 4004) – This bipartisan bill was introduced on June 12 by Rep. Jason Smith (R-MO). The purpose of this bill is to convey approval by Congress of the June 1 trade agreement between the United States and Taiwan. The bill addresses customs administration and regulatory practice issues, as well as dictates conditions for negotiations of subsequent trade agreements. Among its provisions, the bill requires that the U.S. Trade Representative share all negotiating texts with Congress prior to being sent to Taiwan or any parties outside of the executive branch. The bill passed in the House on June 21 and in the Senate on July 18. It was signed into law by the President on Aug. 7.
Providing Accountability Through Transparency Act of 2023 (S 111) – This bill, which was signed into law on July 25, requires each agency to provide a 100-word plain language summary of each new proposed rule posted at regulations.gov. The legislation was introduced by Sen. James Lankford (R-OK) on Jan. 26; passed in the Senate on June 22; and in the House on July 17.
Securing the U.S. Organ Procurement and Transplantation Network Act (HR 2544) – This bipartisan bill was introduced by Rep. Larry Bucshon (R-IN) on April 10. It modifies operations of the Organ Procurement and Transplantation Network, which is managed by the Health Resources and Services Administration (HRSA). In the past, the network of professionals was managed by only one organization, but this new bill allows the HRSA to award multiple grants, contracts or cooperative agreements for network management. The legislation was passed in the House on July 25, in the Senate on July 27 and is currently awaiting signature by President Biden.
Strong Communities Act of 2023 (S 994) – Introduced by Sen. Gary Peters (D-MI) on March 28, this bill permits funding by the Community Oriented Policing Services (COPS) grant program to be used to train officers and recruits who agree to serve in law enforcement agencies in their local communities. The bipartisan bill passed in the Senate on July 26 and is currently under consideration in the House.
Recruit and Retain Act (S 546) – Introduced by Sen. Deb Fischer (R-NE) on Feb. 28, this bill expands the Community Oriented Policing Services (COPS) grant program to enable law enforcement agencies to use funding for recruitment activities such as career and job fairs, as well as lower application fees for things like background checks, testing and psychological evaluations. The Act passed in the Senate on July 26 and has been forwarded to the House.
Department of Veterans Affairs Office of Inspector General Training Act of 2023 (S 1096) – This Act would require new Veterans Affairs (VA) employees to undergo training on how to report misconduct, respond to requests from and cooperate with the Office of the Inspector General. The bill was introduced on March 30 by Sen. Margaret Hassan (D-NH) and was passed in the Senate on July 13. Its fate now rests in the House.
Monitoring Trade Agreements with Taiwan, Promoting Plain-Language Rules, and Expanding Recruiting and Training for Law Enforcement
September 1, 2023 · Blog, Congress at Work, Uncategorized
⏱ 3 min read
United States-Taiwan Initiative on 21st-Century Trade First Agreement Implementation Act (HR 4004) – This bipartisan bill was introduced on June 12 by Rep. Jason Smith (R-MO). The purpose of this bill is to convey approval by Congress of the June 1 trade agreement between the United States and Taiwan. The bill addresses customs administration and regulatory practice issues, as well as dictates conditions for negotiations of subsequent trade agreements. Among its provisions, the bill requires that the U.S. Trade Representative share all negotiating texts with Congress prior to being sent to Taiwan or any parties outside of the executive branch. The bill passed in the House on June 21 and in the Senate on July 18. It was signed into law by the President on Aug. 7.
Providing Accountability Through Transparency Act of 2023 (S 111) – This bill, which was signed into law on July 25, requires each agency to provide a 100-word plain language summary of each new proposed rule posted at regulations.gov. The legislation was introduced by Sen. James Lankford (R-OK) on Jan. 26; passed in the Senate on June 22; and in the House on July 17.
Securing the U.S. Organ Procurement and Transplantation Network Act (HR 2544) – This bipartisan bill was introduced by Rep. Larry Bucshon (R-IN) on April 10. It modifies operations of the Organ Procurement and Transplantation Network, which is managed by the Health Resources and Services Administration (HRSA). In the past, the network of professionals was managed by only one organization, but this new bill allows the HRSA to award multiple grants, contracts or cooperative agreements for network management. The legislation was passed in the House on July 25, in the Senate on July 27 and is currently awaiting signature by President Biden.
Strong Communities Act of 2023 (S 994) – Introduced by Sen. Gary Peters (D-MI) on March 28, this bill permits funding by the Community Oriented Policing Services (COPS) grant program to be used to train officers and recruits who agree to serve in law enforcement agencies in their local communities. The bipartisan bill passed in the Senate on July 26 and is currently under consideration in the House.
Recruit and Retain Act (S 546) – Introduced by Sen. Deb Fischer (R-NE) on Feb. 28, this bill expands the Community Oriented Policing Services (COPS) grant program to enable law enforcement agencies to use funding for recruitment activities such as career and job fairs, as well as lower application fees for things like background checks, testing and psychological evaluations. The Act passed in the Senate on July 26 and has been forwarded to the House.
Department of Veterans Affairs Office of Inspector General Training Act of 2023 (S 1096) – This Act would require new Veterans Affairs (VA) employees to undergo training on how to report misconduct, respond to requests from and cooperate with the Office of the Inspector General. The bill was introduced on March 30 by Sen. Margaret Hassan (D-NH) and was passed in the Senate on July 13. Its fate now rests in the House.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
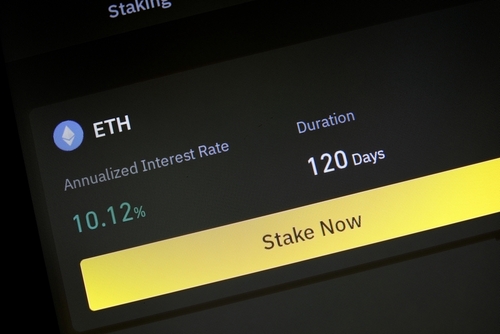
The IRS recently issued an important ruling on the taxability of cryptocurrency staking rewards, determining that staking rewards are essentially “income” and, therefore, taxable upon receipt and not deferrable until sale or swapping. Below, we will look at the ruling in more detail and what it means for taxpayers. But first, let us revisit the concept of cryptocurrency staking as a refresher.
Crypto Staking 101: What Is Staking?
Staking, at its most basic form, is a way for holders of cryptocurrencies to earn rewards or passive income on their digital assets without needing to sell.
One way to think of staking is like a high-yield savings account. When you stake digital assets, you deposit and lock up your coins. This helps run and maintain security on different blockchains (depending on the asset staked). In return, you typically receive more of the digital asset staked.
Rates of return on digital asset staking can be lucrative; however, staking is not without risks.
Staking risks include:
The inherent volatility of cryptocurrencies, where the rewards earned can be less than the change in the underlying digital asset price (causing an overall loss).
Minimum lock-up periods, where staked assets cannot be unstaked and sold or swapped and therefore are illiquid for a period.
Counterparty risk if operating as part of a staking pool, where rewards can be negated as a bad actor and therefore never paid out.
The staking pool or underlying digital asset can be hacked, leading to a loss of funds (remember, there is such a thing as FDIC insurance to protect depositors in the cryptocurrency realm).
Taxability of Staking Rewards
The tax treatment of buying and selling cryptocurrencies is clear. In IRS Notice 2014-21, the government declares that crypto trades should be treated as property, resulting in capital gains treatment like other property bought and sold. Staking, however, is different than trading.
To clarify, given the vague mechanisms of crypto staking, the IRS recently issued a ruling declaring that crypto staking rewards need to be included when received in a taxpayer’s gross income. This ruling formalizes the position taken by the IRS in the Jarrett case.
The argument in the Jarrett case was that the coins received as staking rewards are new property that was created and not the same as income, interest, etc. Essentially, this means the staking rewards are zero-basis assets that would be taxed when sold and not upon receipt. They made the argument that staking rewards were like the products of a baker, where each new cake, although from the same recipe, is a newly created product/asset and, therefore, taxable upon sale.
The court determined that staking rewards, due to their proof-of-stake creation mechanism, are not a new asset, but compensation for helping to maintain and provide validation of the underlying blockchain, with the staked assets used as collateral.
Conclusion
As a result, staking rewards are income when “received.” The taxable amount is the fair market value of the coins when the taxpayer receives the staking reward in an “unlocked” manner. In other words, once the taxpayer controls the staking rewards, the taxpayer is capable (regardless of exercising this capability) of selling them.
IRS Ruling: Crypto Currency Staking Rewards Are Taxable When Received
September 1, 2023 · Blog, Guest Article of the Month, Uncategorized
⏱ 3 min read
The IRS recently issued an important ruling on the taxability of cryptocurrency staking rewards, determining that staking rewards are essentially “income” and, therefore, taxable upon receipt and not deferrable until sale or swapping. Below, we will look at the ruling in more detail and what it means for taxpayers. But first, let us revisit the concept of cryptocurrency staking as a refresher.
Crypto Staking 101: What Is Staking?
Staking, at its most basic form, is a way for holders of cryptocurrencies to earn rewards or passive income on their digital assets without needing to sell.
One way to think of staking is like a high-yield savings account. When you stake digital assets, you deposit and lock up your coins. This helps run and maintain security on different blockchains (depending on the asset staked). In return, you typically receive more of the digital asset staked.
Rates of return on digital asset staking can be lucrative; however, staking is not without risks.
Staking risks include:
The inherent volatility of cryptocurrencies, where the rewards earned can be less than the change in the underlying digital asset price (causing an overall loss).
Minimum lock-up periods, where staked assets cannot be unstaked and sold or swapped and therefore are illiquid for a period.
Counterparty risk if operating as part of a staking pool, where rewards can be negated as a bad actor and therefore never paid out.
The staking pool or underlying digital asset can be hacked, leading to a loss of funds (remember, there is such a thing as FDIC insurance to protect depositors in the cryptocurrency realm).
Taxability of Staking Rewards
The tax treatment of buying and selling cryptocurrencies is clear. In IRS Notice 2014-21, the government declares that crypto trades should be treated as property, resulting in capital gains treatment like other property bought and sold. Staking, however, is different than trading.
To clarify, given the vague mechanisms of crypto staking, the IRS recently issued a ruling declaring that crypto staking rewards need to be included when received in a taxpayer’s gross income. This ruling formalizes the position taken by the IRS in the Jarrett case.
The argument in the Jarrett case was that the coins received as staking rewards are new property that was created and not the same as income, interest, etc. Essentially, this means the staking rewards are zero-basis assets that would be taxed when sold and not upon receipt. They made the argument that staking rewards were like the products of a baker, where each new cake, although from the same recipe, is a newly created product/asset and, therefore, taxable upon sale.
The court determined that staking rewards, due to their proof-of-stake creation mechanism, are not a new asset, but compensation for helping to maintain and provide validation of the underlying blockchain, with the staked assets used as collateral.
Conclusion
As a result, staking rewards are income when “received.” The taxable amount is the fair market value of the coins when the taxpayer receives the staking reward in an “unlocked” manner. In other words, once the taxpayer controls the staking rewards, the taxpayer is capable (regardless of exercising this capability) of selling them.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
When it comes to accounting for capital assets, specifically depreciating capital assets, the Governmental Accounting Standards Board (GASB) provides guidance to state and local governments for accounting processes. The GASB is responsible for the generally accepted accounting principles (GAAP) for the private sector (corporate and business accounting), and it works to promote clear, consistent, transparent, and comparable financial reporting.
One of the three primary GASB pronouncements that impact how these agencies manage their fixed assets includes Statement No. 34, which requires all government entities to use accrual accounting. In addition, such entities must depreciate their capital assets according to its guidelines.
Under the section titled “Basic Financial Statements and Management’s Discussion and Analysis for State and Local Governments,” Statement No. 34 mandates when entities must comply depending on the entity’s annual revenues. Entities with $100 million plus must comply beginning with their first fiscal year after June 15, 2001. Entities with annual revenues of between $10 million and $100 million must comply starting with their first fiscal year post-June 15, 2002. Entities with annual revenues of up to $10 million must comply by their first fiscal year after June 15, 2003.
Capital Assets Overview
The first step in determining a capital asset is to ensure it has a useful life greater than a single reporting period. Examples of capital assets include vehicles, easements, buildings, land and land improvements, and infrastructure (tunnels, bridges, roads, lighting systems, etc.). When defining infrastructure, it must be something that can be used for the long term; generally is stationary, and when a building is looked at, it’s included only if the building is integral to a network of infrastructure assets.
When it comes to reporting capital assets, they should be reported at their historical costs (inclusive of installation and freight charges). For donated assets, they should be recorded at their fair market value at time received.
Depreciation Expense Reporting Considerations
When an asset is identified with a specific function, it’s recommended to be a direct expense. This includes appropriate assets that are attributable to a unique department or role. If the asset is used by many different departments and there are depreciation expenses, they should be proportionate to how each department uses the respective assets. Additionally, if an asset function across multiple departments or across citywide functions, its depreciation expense is not categorized as a direct expense but rather as a separate line in the Statement of Activities.
Whether it’s straight or declining balance methods (such as double declining balance and 150 percent declining balance), it is done over the asset’s useful life. When it comes to determining an asset’s useful life, government entities can base their calculations on their own past internal experience for similar needs, how other government entities treated similar asset classifications that are publicly available, or industry or professional organization’s published guidelines. Condition and the expected service life are two important factors to be considered.
Another important factor in how depreciation is calculated depends on how assets themselves are classified. For example, it can be done through the following lenses:
Individual assets
Classes of assets
Networks of assets
Subsystems of a network of assets
Looking at the last two ways to analyze these assets for depreciation, rural roads, state highways, and Interstate highways can be broken down into three discrete systems, also referred to as a subsystem of the network. However, if all three different transportation systems are grouped together, the bigger system would be a network of infrastructure assets or a network of assets.
With capital assets expected to be a part of governments’ budgets, understanding the intricacies is essential to ensure standards are met.
How to Account for Capital Assets
August 1, 2023 · Accounting News, Blog, Uncategorized
⏱ 4 min read
When it comes to accounting for capital assets, specifically depreciating capital assets, the Governmental Accounting Standards Board (GASB) provides guidance to state and local governments for accounting processes. The GASB is responsible for the generally accepted accounting principles (GAAP) for the private sector (corporate and business accounting), and it works to promote clear, consistent, transparent, and comparable financial reporting.
One of the three primary GASB pronouncements that impact how these agencies manage their fixed assets includes Statement No. 34, which requires all government entities to use accrual accounting. In addition, such entities must depreciate their capital assets according to its guidelines.
Under the section titled “Basic Financial Statements and Management’s Discussion and Analysis for State and Local Governments,” Statement No. 34 mandates when entities must comply depending on the entity’s annual revenues. Entities with $100 million plus must comply beginning with their first fiscal year after June 15, 2001. Entities with annual revenues of between $10 million and $100 million must comply starting with their first fiscal year post-June 15, 2002. Entities with annual revenues of up to $10 million must comply by their first fiscal year after June 15, 2003.
Capital Assets Overview
The first step in determining a capital asset is to ensure it has a useful life greater than a single reporting period. Examples of capital assets include vehicles, easements, buildings, land and land improvements, and infrastructure (tunnels, bridges, roads, lighting systems, etc.). When defining infrastructure, it must be something that can be used for the long term; generally is stationary, and when a building is looked at, it’s included only if the building is integral to a network of infrastructure assets.
When it comes to reporting capital assets, they should be reported at their historical costs (inclusive of installation and freight charges). For donated assets, they should be recorded at their fair market value at time received.
Depreciation Expense Reporting Considerations
When an asset is identified with a specific function, it’s recommended to be a direct expense. This includes appropriate assets that are attributable to a unique department or role. If the asset is used by many different departments and there are depreciation expenses, they should be proportionate to how each department uses the respective assets. Additionally, if an asset function across multiple departments or across citywide functions, its depreciation expense is not categorized as a direct expense but rather as a separate line in the Statement of Activities.
Whether it’s straight or declining balance methods (such as double declining balance and 150 percent declining balance), it is done over the asset’s useful life. When it comes to determining an asset’s useful life, government entities can base their calculations on their own past internal experience for similar needs, how other government entities treated similar asset classifications that are publicly available, or industry or professional organization’s published guidelines. Condition and the expected service life are two important factors to be considered.
Another important factor in how depreciation is calculated depends on how assets themselves are classified. For example, it can be done through the following lenses:
Individual assets
Classes of assets
Networks of assets
Subsystems of a network of assets
Looking at the last two ways to analyze these assets for depreciation, rural roads, state highways, and Interstate highways can be broken down into three discrete systems, also referred to as a subsystem of the network. However, if all three different transportation systems are grouped together, the bigger system would be a network of infrastructure assets or a network of assets.
With capital assets expected to be a part of governments’ budgets, understanding the intricacies is essential to ensure standards are met.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
In light of our current economy, making sure your money works hard for you is one of the best things to do this year. Here are some ways you can navigate your financial situation, keep tabs on where you are, and adjust if you need to.
Shop for a higher return on savings. These days, every extra cent counts. That’s why it pays to look around for higher rates on savings accounts. Several places to check out are PNC (4.65 percent APY), Sofi (up to 4.4 percent APY), and American Express (4 percent APY). Here are a few others. Rates may increase even more with the Federal Reserve’s rate hike announcement on July 27.
Open an HSA account. When you have one of these, it will help you pay for expenses that your health insurance plan doesn’t cover. If you’re enrolled in a high-deductible insurance plan, you and possibly your employer can contribute pre-tax dollars into this account, from which you’ll use funds you’ve stocked away for qualified medical expenses. Whatever money you don’t use will roll over to the next year, unlike FSA accounts.
Consolidate debt. Why pay a bunch of different interest rates on all your credit cards? If you have debt, find one card with a very low-interest rate and do a balance transfer. Some credit cards offer 0 percent APR as an introductory rate, which will be a big savings to get a jumpstart on becoming debt-free. Here are a few good ones: Bank of America® Travel Rewards Credit Card now offers 0 percent APR for 18 months. Discover it® Cash Back offers 0 percent APR for 15 months. Find other great deals here.
Cut how much you pay on car insurance. Have you shopped around lately? We know this might seem like a pain, as it takes a lot of time, but here’s some good news, and it’s called The Zebra. This amazing site has done all the heavy lifting for you. Here, you’ll find dozens of real-time comparisons from many trusted companies.
Max out your 401K. This year, the maximum yearly contribution limit has been raised by $200 to $22,500 (up from $20,500 in 2022). Even better, if you’re over 50, you can set aside catch-up contributions of $7,500, allowing a total contribution of up to $30,000. This allowance lets older workers add as much as they can so that when they retire, they’ll be in a better financial situation.
Update your W-4. No one likes a shock when it comes to paying taxes. That’s why this is such a smart idea. And the IRS actually has a tool that can help you: The Tax Withholding Estimator. Go here to find out if your employer is taking enough money out for taxes. If you’re falling short, you’ll know. Better to learn and fix this before it’s too late.
Create a net worth statement. When you have a realistic idea of your assets and liabilities, you’ll be able to see whether or not you’re on the right track with retirement. This way, you’ll be able to set up new goals for yourself if you feel you need to.
Keeping up with your finances, while time-consuming, really pays off. If you try one (or all) of these hacks, you’ll be better off in no time.
August 1, 2023 · Blog, Tip of the Month, Uncategorized
⏱ 3 min read
In light of our current economy, making sure your money works hard for you is one of the best things to do this year. Here are some ways you can navigate your financial situation, keep tabs on where you are, and adjust if you need to.
Shop for a higher return on savings. These days, every extra cent counts. That’s why it pays to look around for higher rates on savings accounts. Several places to check out are PNC (4.65 percent APY), Sofi (up to 4.4 percent APY), and American Express (4 percent APY). Here are a few others. Rates may increase even more with the Federal Reserve’s rate hike announcement on July 27.
Open an HSA account. When you have one of these, it will help you pay for expenses that your health insurance plan doesn’t cover. If you’re enrolled in a high-deductible insurance plan, you and possibly your employer can contribute pre-tax dollars into this account, from which you’ll use funds you’ve stocked away for qualified medical expenses. Whatever money you don’t use will roll over to the next year, unlike FSA accounts.
Consolidate debt. Why pay a bunch of different interest rates on all your credit cards? If you have debt, find one card with a very low-interest rate and do a balance transfer. Some credit cards offer 0 percent APR as an introductory rate, which will be a big savings to get a jumpstart on becoming debt-free. Here are a few good ones: Bank of America® Travel Rewards Credit Card now offers 0 percent APR for 18 months. Discover it® Cash Back offers 0 percent APR for 15 months. Find other great deals here.
Cut how much you pay on car insurance. Have you shopped around lately? We know this might seem like a pain, as it takes a lot of time, but here’s some good news, and it’s called The Zebra. This amazing site has done all the heavy lifting for you. Here, you’ll find dozens of real-time comparisons from many trusted companies.
Max out your 401K. This year, the maximum yearly contribution limit has been raised by $200 to $22,500 (up from $20,500 in 2022). Even better, if you’re over 50, you can set aside catch-up contributions of $7,500, allowing a total contribution of up to $30,000. This allowance lets older workers add as much as they can so that when they retire, they’ll be in a better financial situation.
Update your W-4. No one likes a shock when it comes to paying taxes. That’s why this is such a smart idea. And the IRS actually has a tool that can help you: The Tax Withholding Estimator. Go here to find out if your employer is taking enough money out for taxes. If you’re falling short, you’ll know. Better to learn and fix this before it’s too late.
Create a net worth statement. When you have a realistic idea of your assets and liabilities, you’ll be able to see whether or not you’re on the right track with retirement. This way, you’ll be able to set up new goals for yourself if you feel you need to.
Keeping up with your finances, while time-consuming, really pays off. If you try one (or all) of these hacks, you’ll be better off in no time.
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Now that we are heading into the backend of summer, it’s time for many states to host their annual sales tax holidays for returning to-school shopping. Numerous states with sales tax (remember, not all states have a sales tax) provide the reprieve to help families with the cost of annual school supplies and clothing.
According to the National Retail Federation, nearly 80 percent of shoppers are expecting increased costs this year versus last year; so more than ever, consumers are looking for ways to save. Furthermore, about two-thirds of back-to-school shoppers take advantage of these tax-free shopping periods.
The vast majority of states offer some type of tax-free shopping for a limited time period, frequently taking place over a weekend. Below, we will look at each state that offers a sales tax holiday for back-to-school shoppers, along with their details. Note that several states, including Alabama, Mississippi, and Tennessee, have their programs in July – and those are excluded from this article due to the timing of publication.
State Programs
Arkansas: From Aug. 5-6, the following items are tax-free for shoppers: clothes and shoes under $100 per piece, fashion accessories $50 and less per piece, as well as electronics, art, and school supplies.
Connecticut: From Aug. 20-26, clothes and shoes priced at $100 or less per piece are tax-exempt. Fashion accessories and sports gear are fully taxable, though.
Iowa: Aug. 4-5, clothes and shoes priced at $100 or less per piece are exempt.
Maryland: From Aug. 13-19, clothes and shoes priced at $100 or less per piece are exempt.
Missouri’s back-to-school tax breaks come Aug. 4-6. Clothes that cost less than $100 per piece are exempt. Also tax exempt on a “per purchase basis” are school supplies under $50, software under $350, and PCs under $1,500.
New Jersey: From Aug. 26 to Sept. 4 all art supplies, instructional materials, school supplies, and sports equipment sold to individuals are sales tax exempt. In addition, computers priced at $3,000 or less are also tax-free.
New Mexico cuts its sales tax charges from Aug. 4-6. Included are clothes, shoes, and backpacks costing $100 or less per piece; school supplies costing $30 or less per piece; and computers costing less than $1,000.
Ohio’s back-to-school deals are during Aug. 4-6. Clothes costing $75 or less per piece; school supplies less than $20; and other instructional materials priced at $20 or less are all tax-free.
Oklahoma from August 4-6; only clothes and shoes costing $100 or less per piece are exempt.
Texas: During Aug. 11-13, clothing, footwear, school supplies, and backpacks priced below $100 per piece are exempt. The exemption applies to both brick-and-mortar sales and those made online or via catalog.
West Virginia: From Aug. 4-7, no sales tax is charged for clothing priced at $125 or less; laptops and tablets costing $500 or less; school supplies purchased for $50 or less; and also certain sports equipment costing $150 or less.
Expirations and Details
If you notice, most states have an exemption for clothes and footwear in a moderate price range. Some are more liberal with their exemptions, while others offer a tax break on a broader scope of items, such as electronics and supplies.
Keep in mind that a few states’ sales tax holidays are permanent, while others are temporary. Also, remember that certain states are very specific about what is exempt from sales tax, so visit your state’s tax revenue website for details. It’s also important to note that some states allow counties or towns to exempt themselves, so check for this provision as well.
2023 Sales Tax Holidays for Back-to-School Shopping
August 1, 2023 · Blog, Tax and Financial News, Uncategorized
⏱ 3 min read
Now that we are heading into the backend of summer, it’s time for many states to host their annual sales tax holidays for returning to-school shopping. Numerous states with sales tax (remember, not all states have a sales tax) provide the reprieve to help families with the cost of annual school supplies and clothing.
According to the National Retail Federation, nearly 80 percent of shoppers are expecting increased costs this year versus last year; so more than ever, consumers are looking for ways to save. Furthermore, about two-thirds of back-to-school shoppers take advantage of these tax-free shopping periods.
The vast majority of states offer some type of tax-free shopping for a limited time period, frequently taking place over a weekend. Below, we will look at each state that offers a sales tax holiday for back-to-school shoppers, along with their details. Note that several states, including Alabama, Mississippi, and Tennessee, have their programs in July – and those are excluded from this article due to the timing of publication.
State Programs
Arkansas: From Aug. 5-6, the following items are tax-free for shoppers: clothes and shoes under $100 per piece, fashion accessories $50 and less per piece, as well as electronics, art, and school supplies.
Connecticut: From Aug. 20-26, clothes and shoes priced at $100 or less per piece are tax-exempt. Fashion accessories and sports gear are fully taxable, though.
Iowa: Aug. 4-5, clothes and shoes priced at $100 or less per piece are exempt.
Maryland: From Aug. 13-19, clothes and shoes priced at $100 or less per piece are exempt.
Missouri’s back-to-school tax breaks come Aug. 4-6. Clothes that cost less than $100 per piece are exempt. Also tax exempt on a “per purchase basis” are school supplies under $50, software under $350, and PCs under $1,500.
New Jersey: From Aug. 26 to Sept. 4 all art supplies, instructional materials, school supplies, and sports equipment sold to individuals are sales tax exempt. In addition, computers priced at $3,000 or less are also tax-free.
New Mexico cuts its sales tax charges from Aug. 4-6. Included are clothes, shoes, and backpacks costing $100 or less per piece; school supplies costing $30 or less per piece; and computers costing less than $1,000.
Ohio’s back-to-school deals are during Aug. 4-6. Clothes costing $75 or less per piece; school supplies less than $20; and other instructional materials priced at $20 or less are all tax-free.
Oklahoma from August 4-6; only clothes and shoes costing $100 or less per piece are exempt.
Texas: During Aug. 11-13, clothing, footwear, school supplies, and backpacks priced below $100 per piece are exempt. The exemption applies to both brick-and-mortar sales and those made online or via catalog.
West Virginia: From Aug. 4-7, no sales tax is charged for clothing priced at $125 or less; laptops and tablets costing $500 or less; school supplies purchased for $50 or less; and also certain sports equipment costing $150 or less.
Expirations and Details
If you notice, most states have an exemption for clothes and footwear in a moderate price range. Some are more liberal with their exemptions, while others offer a tax break on a broader scope of items, such as electronics and supplies.
Keep in mind that a few states’ sales tax holidays are permanent, while others are temporary. Also, remember that certain states are very specific about what is exempt from sales tax, so visit your state’s tax revenue website for details. It’s also important to note that some states allow counties or towns to exempt themselves, so check for this provision as well.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
 United States-Taiwan Initiative on 21st-Century Trade First Agreement Implementation Act (HR 4004) – This bipartisan bill was introduced on June 12 by Rep. Jason Smith (R-MO). The purpose of this bill is to convey approval by Congress of the June 1 trade agreement between the United States and Taiwan. The bill addresses customs administration and regulatory practice issues, as well as dictates conditions for negotiations of subsequent trade agreements. Among its provisions, the bill requires that the U.S. Trade Representative share all negotiating texts with Congress prior to being sent to Taiwan or any parties outside of the executive branch. The bill passed in the House on June 21 and in the Senate on July 18. It was signed into law by the President on Aug. 7.



 The IRS recently issued an important ruling on the taxability of cryptocurrency staking rewards, determining that staking rewards are essentially “income” and, therefore, taxable upon receipt and not deferrable until sale or swapping. Below, we will look at the ruling in more detail and what it means for taxpayers. But first, let us revisit the concept of cryptocurrency staking as a refresher.
 When it comes to accounting for capital assets, specifically depreciating capital assets, the Governmental Accounting Standards Board (GASB) provides guidance to state and local governments for accounting processes. The GASB is responsible for the generally accepted accounting principles (GAAP) for the private sector (corporate and business accounting), and it works to promote clear, consistent, transparent, and comparable financial reporting.
 In light of our current economy, making sure your money works hard for you is one of the best things to do this year. Here are some ways you can navigate your financial situation, keep tabs on where you are, and adjust if you need to.
 Now that we are heading into the backend of summer, it’s time for many states to host their annual sales tax holidays for returning to-school shopping. Numerous states with sales tax (remember, not all states have a sales tax) provide the reprieve to help families with the cost of annual school supplies and clothing.