Continuing Appropriations and Extensions Act, 2025 (HR 9747) – This continuing resolution was introduced on Sept. 22 as a “clean” extenuation of the federal budget to fund the government until Dec. 20. Up until this point, a handful of Republicans had attached unrelated bills pertaining to November election restrictions, which they did not have the votes to pass in the House and would never have passed in the Senate. After several weeks of threatening to shut down the government by not passing a continuing appropriations bill, the House Speaker proposed this “last-minute” tied over with the minimum appropriations necessary to keep the government up and running. While it still does not solidify the federal budget for the 2025 fiscal year (Sept. 29, 2024, through Sept. 27, 2025), this bill is expected to pass in the House on Sept. 25 and to clear the Senate and be signed by the president by Sept. 29.
Preventing the Financing of Illegal Synthetic Drugs Act (HR 1076) – Introduced by Rep. Mónica De La Cruz (R-TX) on Feb. 17, 2023, this bill directs the Government Accountability Office to conduct a study on illegal funding sources related to the trafficking of synthetic drugs such fentanyl and methamphetamine. The bill passed in the House on May 22, 2023, in the Senate on July 23, 2024, and was signed into law by the president on Sept. 13.
Launch Communications Act (S 1648) – This act will update ground-to-space rocket communications going forward. Presently, commercial missions are required to use the government-owned spectrum to communicate during launches, including special temporary authority for private companies. This bill permits the Federal Communications Commission (FCC) to facilitate seamless access to broadband spectrum frequencies for commercial space launches and re-entries. The bill, which was introduced on May 17, 2023, by Sen. Eric Schmitt (R-MO), passed unanimously in the Senate on Oct. 21, 2023, and in the House on Sept. 17. It is currently awaiting signature by the president for enactment.
FUTURE Networks Act (HR 1513) – The acronym stands for Future Uses of Technology Upholding Reliable and Enhanced Networks Act. Introduced by Doris Matsui (D-CA) on March 9, 2023, this act would instruct the Federal Communications Commission (FCC) to establish a 6G Task Force comprised of private, academic and government experts to monitor the status of sixth-generation wireless technology, including its possible uses. The House passed the bill on Sept. 18, and the bill now rests with the Senate.
Violence Against Women by Illegal Aliens Act (HR 7909) – This bill would amend the Immigration and Nationality Act to make non-U.S. nationals (aliens) convicted of or having admitted to committing sex offenses or domestic violence (including conspiracy to commit a sex offense) be ineligible for country admission and deportable. Introduced by Rep. Nancy Mace (R-SC), the bill passed in the House on Sept. 18 and currently lies in the Senate.
Intergovernmental Critical Minerals Task Force Act (S 1871) – Introduced by Sen. Gary Peters (D-MI) on June 8, 2023, this bill would enable coordination among state, local, tribal and territorial jurisdictions with the federal government to mitigate national security risks related to the current U.S. critical mineral supply chains. Specifically, the intent is to make the United States less reliant on China and other countries for critical minerals and rare earth metals. Provisions of the bill allow for development, mining and strengthening of our domestic workforce and to improve partnerships with allied countries for dependable mineral supply chains. The bill passed in the Senate on Sept. 8 and is currently with the House.
SMART Leasing Act (S 211) – Introduced on Feb. 1, 2023, by Sen. Gary Peters (D-MI), this bill would launch a program to lease underutilized properties owned by the federal government. The net funding would then be used for capital projects and to help offset the national deficit. The act passed in the Senate on Aug. 1 and is currently under consideration in the House.
Keeping the Government Open, Stopping the Flow of Synthetic Drugs, and Improving Wireless Communications on Land and in Space
October 1, 2024 · Blog, Congress at Work, Uncategorized
⏱ 4 min read
Continuing Appropriations and Extensions Act, 2025 (HR 9747) – This continuing resolution was introduced on Sept. 22 as a “clean” extenuation of the federal budget to fund the government until Dec. 20. Up until this point, a handful of Republicans had attached unrelated bills pertaining to November election restrictions, which they did not have the votes to pass in the House and would never have passed in the Senate. After several weeks of threatening to shut down the government by not passing a continuing appropriations bill, the House Speaker proposed this “last-minute” tied over with the minimum appropriations necessary to keep the government up and running. While it still does not solidify the federal budget for the 2025 fiscal year (Sept. 29, 2024, through Sept. 27, 2025), this bill is expected to pass in the House on Sept. 25 and to clear the Senate and be signed by the president by Sept. 29.
Preventing the Financing of Illegal Synthetic Drugs Act (HR 1076) – Introduced by Rep. Mónica De La Cruz (R-TX) on Feb. 17, 2023, this bill directs the Government Accountability Office to conduct a study on illegal funding sources related to the trafficking of synthetic drugs such fentanyl and methamphetamine. The bill passed in the House on May 22, 2023, in the Senate on July 23, 2024, and was signed into law by the president on Sept. 13.
Launch Communications Act (S 1648) – This act will update ground-to-space rocket communications going forward. Presently, commercial missions are required to use the government-owned spectrum to communicate during launches, including special temporary authority for private companies. This bill permits the Federal Communications Commission (FCC) to facilitate seamless access to broadband spectrum frequencies for commercial space launches and re-entries. The bill, which was introduced on May 17, 2023, by Sen. Eric Schmitt (R-MO), passed unanimously in the Senate on Oct. 21, 2023, and in the House on Sept. 17. It is currently awaiting signature by the president for enactment.
FUTURE Networks Act (HR 1513) – The acronym stands for Future Uses of Technology Upholding Reliable and Enhanced Networks Act. Introduced by Doris Matsui (D-CA) on March 9, 2023, this act would instruct the Federal Communications Commission (FCC) to establish a 6G Task Force comprised of private, academic and government experts to monitor the status of sixth-generation wireless technology, including its possible uses. The House passed the bill on Sept. 18, and the bill now rests with the Senate.
Violence Against Women by Illegal Aliens Act (HR 7909) – This bill would amend the Immigration and Nationality Act to make non-U.S. nationals (aliens) convicted of or having admitted to committing sex offenses or domestic violence (including conspiracy to commit a sex offense) be ineligible for country admission and deportable. Introduced by Rep. Nancy Mace (R-SC), the bill passed in the House on Sept. 18 and currently lies in the Senate.
Intergovernmental Critical Minerals Task Force Act (S 1871) – Introduced by Sen. Gary Peters (D-MI) on June 8, 2023, this bill would enable coordination among state, local, tribal and territorial jurisdictions with the federal government to mitigate national security risks related to the current U.S. critical mineral supply chains. Specifically, the intent is to make the United States less reliant on China and other countries for critical minerals and rare earth metals. Provisions of the bill allow for development, mining and strengthening of our domestic workforce and to improve partnerships with allied countries for dependable mineral supply chains. The bill passed in the Senate on Sept. 8 and is currently with the House.
SMART Leasing Act (S 211) – Introduced on Feb. 1, 2023, by Sen. Gary Peters (D-MI), this bill would launch a program to lease underutilized properties owned by the federal government. The net funding would then be used for capital projects and to help offset the national deficit. The act passed in the Senate on Aug. 1 and is currently under consideration in the House.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
The value of an estate plan is twofold. Yes, you want to pass your assets on to heirs in a seamless and tax-efficient manner. But it is also a roadmap to help your heirs understand the full breadth of your assets, where they are located, and how they should be disseminated according to your wishes.
Two important components of your estate plan come into play before you pass away. The first is a Power of Attorney. This document appoints someone you trust – a relative, a friend or a custodial like a bank – to handle your finances on your behalf should you become incapacitated. The second is a Health Care Directive, in which you name someone to make medical decisions for you when you no longer can. To accompany this document, you also may want to complete a living will, generally a boilerplate form that lets medical providers know if you want to forgo life-saving procedures and treatments if you’re in a terminal condition, a coma or near the end of life. Also known as a DNR (do not resuscitate), this document dictates your wishes rather than placing the burden on someone else.
Write a Last Will and Testament
The more complex the estate, the more likely you will need an estate attorney to help you. However, in many cases, an individual can create a will on his own using state-provided forms. The most important thing to remember is that each state has its own requirements regarding wills, such as whether it can be handwritten or even digital and who and how it should be witnessed and possibly notarized. Every time you move to another state throughout your lifetime, you’ll need to update or replace your will to reflect your new home state’s rules.
Your will should name an executor or personal representative in charge of executing the will’s instructions. If you are not married and have minor children, you’ll need to name a guardian for them once you’re deceased. Note that while the age of majority is generally 18, this can vary by state or jurisdiction. Your will should instruct how your assets should be disseminated and to whom, including contingent beneficiaries (should your first choice die before you), and specifically name anyone whom you don’t want to receive proceeds. For example, without a will as a guide, a probate judge may decide that a step-brother should receive your assets instead of your best friend since he is technically a relative.
Be aware that the beneficiary designations on your accounts (e.g., bank, investment, insurance policies) supersede instructions in your will. For example, if you want your second wife to be the sole beneficiary of your assets but forget to change her as the beneficiary on your 401(k) account, your ex will get the payout. That’s the same for all of your accounts with a named beneficiary, so every time you remarry or experience other life-altering events, be sure to review your account beneficiaries and estate plan documents.
Also, make it easy for your executor to find the documents needed to liquidate and/or transfer assets. A simple way to do this is to keep a three-ring binder or file drawer that houses documents/statements for each of your assets, including banking and investment accounts, former and current employer retirement plans, life insurance policies, annuities, real estate property records, etc. If you have a home or property that needs to be sold with proceeds split among your heirs, you should keep records to help establish the property’s cost basis. This includes the sale price and closing expenses from when you purchased the home, as well as the cost of any major repairs or renovations (e.g., new roof, HVAC, additional rooms). When the house is sold, the amount of the sale price minus the cost basis will determine whether or not capital gains need to be paid. Note that taxes on property and investments will need to be paid before assets can be disseminated to your heirs.
Your will is designed to guide a probate judge so that your estate can be settled quickly. However, if you want your heirs to have access to your assets without being subject to probate, consider naming them as joint account owners on your bank and investment accounts as well as the deeds to your properties.
With larger or more complex estates, you might want to consider a trust. Estate planning trusts vary by the type of beneficiary, payout structure, and tax benefit. A trust avoids probate and can help minimize the tax burden on your accumulated assets. Bear in mind that there are dozens of different types of trusts for different circumstances, so it’s important to work with an experienced estate attorney to determine what works best for your situation.
Remember, your estate plan should be a living document that is reviewed and updated every few years to incorporate any new changes in your life, including marriage, children, divorce, and death.
Pre-Retirement Planning Guide Estate Plan
October 1, 2024 · Blog, Financial Planning, Uncategorized
⏱ 5 min read
Step 5: Estate Plan
The value of an estate plan is twofold. Yes, you want to pass your assets on to heirs in a seamless and tax-efficient manner. But it is also a roadmap to help your heirs understand the full breadth of your assets, where they are located, and how they should be disseminated according to your wishes.
Two important components of your estate plan come into play before you pass away. The first is a Power of Attorney. This document appoints someone you trust – a relative, a friend or a custodial like a bank – to handle your finances on your behalf should you become incapacitated. The second is a Health Care Directive, in which you name someone to make medical decisions for you when you no longer can. To accompany this document, you also may want to complete a living will, generally a boilerplate form that lets medical providers know if you want to forgo life-saving procedures and treatments if you’re in a terminal condition, a coma or near the end of life. Also known as a DNR (do not resuscitate), this document dictates your wishes rather than placing the burden on someone else.
Write a Last Will and Testament
The more complex the estate, the more likely you will need an estate attorney to help you. However, in many cases, an individual can create a will on his own using state-provided forms. The most important thing to remember is that each state has its own requirements regarding wills, such as whether it can be handwritten or even digital and who and how it should be witnessed and possibly notarized. Every time you move to another state throughout your lifetime, you’ll need to update or replace your will to reflect your new home state’s rules.
Your will should name an executor or personal representative in charge of executing the will’s instructions. If you are not married and have minor children, you’ll need to name a guardian for them once you’re deceased. Note that while the age of majority is generally 18, this can vary by state or jurisdiction. Your will should instruct how your assets should be disseminated and to whom, including contingent beneficiaries (should your first choice die before you), and specifically name anyone whom you don’t want to receive proceeds. For example, without a will as a guide, a probate judge may decide that a step-brother should receive your assets instead of your best friend since he is technically a relative.
Be aware that the beneficiary designations on your accounts (e.g., bank, investment, insurance policies) supersede instructions in your will. For example, if you want your second wife to be the sole beneficiary of your assets but forget to change her as the beneficiary on your 401(k) account, your ex will get the payout. That’s the same for all of your accounts with a named beneficiary, so every time you remarry or experience other life-altering events, be sure to review your account beneficiaries and estate plan documents.
Also, make it easy for your executor to find the documents needed to liquidate and/or transfer assets. A simple way to do this is to keep a three-ring binder or file drawer that houses documents/statements for each of your assets, including banking and investment accounts, former and current employer retirement plans, life insurance policies, annuities, real estate property records, etc. If you have a home or property that needs to be sold with proceeds split among your heirs, you should keep records to help establish the property’s cost basis. This includes the sale price and closing expenses from when you purchased the home, as well as the cost of any major repairs or renovations (e.g., new roof, HVAC, additional rooms). When the house is sold, the amount of the sale price minus the cost basis will determine whether or not capital gains need to be paid. Note that taxes on property and investments will need to be paid before assets can be disseminated to your heirs.
Your will is designed to guide a probate judge so that your estate can be settled quickly. However, if you want your heirs to have access to your assets without being subject to probate, consider naming them as joint account owners on your bank and investment accounts as well as the deeds to your properties.
With larger or more complex estates, you might want to consider a trust. Estate planning trusts vary by the type of beneficiary, payout structure, and tax benefit. A trust avoids probate and can help minimize the tax burden on your accumulated assets. Bear in mind that there are dozens of different types of trusts for different circumstances, so it’s important to work with an experienced estate attorney to determine what works best for your situation.
Remember, your estate plan should be a living document that is reviewed and updated every few years to incorporate any new changes in your life, including marriage, children, divorce, and death.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
With more than 14 million electric vehicle (EV) registrations in 2023 worldwide and 2023 seeing an increase in EV sales over 2022 by 35 percent, manufacturers are probably happy – but not those producing the traditional internal combustion engine (ICE) vehicles. This is according to the International Energy Agency’s Global EV Outlook 2024: Trends in Electric Cars.
This statistic is important because it illustrates how assets can be rendered less useful and potentially turn into stranded assets. A stranded asset, defined, is an asset that’s no longer able to provide its owner the profitable payback they originally expected. The difference is based on shifts, primarily negative, that impact the asset’s expected productive performance.
How & Why Assets Become Stranded
When an asset loses its earning power, normally due to extraneous circumstances, like the invention of a more efficient battery, it can become stranded. For example, a machine that’s exclusively capable of making an internal combustion engine (ICE) vehicle can be considered stranded as the transition to electric vehicles (EV) is made. Since the machine is less valuable because it makes fewer and fewer ICE vehicles, it could be impaired or stranded.
This example illustrates that new technology, especially one that moves forward, can render equipment less useful than previously expected. Other ways assets can be stranded include administrative modifications, evolving societal conventions, etc.
Considerations for Stranded Assets by Testing an Asset for Impairment
The primary way to establish if an asset is stranded is to run an impairment test on it. Stranded assets impact the income statement via a non-cash loss, along with impacting the balance sheet by reducing asset value. Therefore, companies must report a loss on the income statement as it’s completely written off the balance sheet.
Whether it’s through the lens of International Financial Reporting Standards (IFRS) or generally accepted accounting principles (GAAP), whether an asset is intangible or tangible, when its value issue is less than book value or impaired, it must be written down.
GAAP Standard
The first step is to determine the carrying value. This is calculated by subtracting the accumulated depreciation from the asset’s original cost. From there, the asset’s projected undiscounted future cash flows (UFCF) are analyzed against the asset’s carrying value. If the total UFCF is less than the carrying value, an asset is considered impaired.
IFRS Standard
The first step also looks at an asset’s carrying value. From there, if either of the following two values is lower than the carrying value, it’s considered impaired:
Present value of future cash flows generated by the asset (the so-called “fair value in use” consideration)
Fair value less costs to sell the asset
Financial Statement Considerations
If an asset is impaired or stranded, whatever amount the asset drops by, it lowers the business’ asset’s value on the balance sheet. Looking at the income statement, it’s considered a loss. Additionally, since a devaluation is not considered a cash event, it doesn’t trigger any cash outflows. A real-world example can better illustrate this.
The following assumes a business reports its accounting under GAAP. It could be a company that produces fracking equipment to recover natural gas and crude oil. With the uncertainty of domestic fossil fuel policy, specifically where land can be explored, the threat of OPEC and/or Iran being able to determine their production, and the threat of increased government spending on green energy, fracking equipment has a current carrying value of $10 million. However, with increased competition from the three different factors, the same assets can produce an aggregate of $7.5 million in undiscounted future cash flows.
Based on GAAP, since the carrying value is $2.5 million more than the total undiscounted future cash flows, the business would need to record the same amount for an impairment loss. The journal entries would be:
Loss from Impairment Debit:. $2.5 million
Provision for Impairment Losses Credit: $2.5 million
Conclusion
When it comes to accounting for stranded assets, it’s important to ensure guidelines are followed based on the type of accounting standards businesses must follow.
How to Account for Stranded Assets
October 1, 2024 · Accounting News, Blog, Uncategorized
⏱ 4 min read
With more than 14 million electric vehicle (EV) registrations in 2023 worldwide and 2023 seeing an increase in EV sales over 2022 by 35 percent, manufacturers are probably happy – but not those producing the traditional internal combustion engine (ICE) vehicles. This is according to the International Energy Agency’s Global EV Outlook 2024: Trends in Electric Cars.
This statistic is important because it illustrates how assets can be rendered less useful and potentially turn into stranded assets. A stranded asset, defined, is an asset that’s no longer able to provide its owner the profitable payback they originally expected. The difference is based on shifts, primarily negative, that impact the asset’s expected productive performance.
How & Why Assets Become Stranded
When an asset loses its earning power, normally due to extraneous circumstances, like the invention of a more efficient battery, it can become stranded. For example, a machine that’s exclusively capable of making an internal combustion engine (ICE) vehicle can be considered stranded as the transition to electric vehicles (EV) is made. Since the machine is less valuable because it makes fewer and fewer ICE vehicles, it could be impaired or stranded.
This example illustrates that new technology, especially one that moves forward, can render equipment less useful than previously expected. Other ways assets can be stranded include administrative modifications, evolving societal conventions, etc.
Considerations for Stranded Assets by Testing an Asset for Impairment
The primary way to establish if an asset is stranded is to run an impairment test on it. Stranded assets impact the income statement via a non-cash loss, along with impacting the balance sheet by reducing asset value. Therefore, companies must report a loss on the income statement as it’s completely written off the balance sheet.
Whether it’s through the lens of International Financial Reporting Standards (IFRS) or generally accepted accounting principles (GAAP), whether an asset is intangible or tangible, when its value issue is less than book value or impaired, it must be written down.
GAAP Standard
The first step is to determine the carrying value. This is calculated by subtracting the accumulated depreciation from the asset’s original cost. From there, the asset’s projected undiscounted future cash flows (UFCF) are analyzed against the asset’s carrying value. If the total UFCF is less than the carrying value, an asset is considered impaired.
IFRS Standard
The first step also looks at an asset’s carrying value. From there, if either of the following two values is lower than the carrying value, it’s considered impaired:
Present value of future cash flows generated by the asset (the so-called “fair value in use” consideration)
Fair value less costs to sell the asset
Financial Statement Considerations
If an asset is impaired or stranded, whatever amount the asset drops by, it lowers the business’ asset’s value on the balance sheet. Looking at the income statement, it’s considered a loss. Additionally, since a devaluation is not considered a cash event, it doesn’t trigger any cash outflows. A real-world example can better illustrate this.
The following assumes a business reports its accounting under GAAP. It could be a company that produces fracking equipment to recover natural gas and crude oil. With the uncertainty of domestic fossil fuel policy, specifically where land can be explored, the threat of OPEC and/or Iran being able to determine their production, and the threat of increased government spending on green energy, fracking equipment has a current carrying value of $10 million. However, with increased competition from the three different factors, the same assets can produce an aggregate of $7.5 million in undiscounted future cash flows.
Based on GAAP, since the carrying value is $2.5 million more than the total undiscounted future cash flows, the business would need to record the same amount for an impairment loss. The journal entries would be:
Loss from Impairment Debit:. $2.5 million
Provision for Impairment Losses Credit: $2.5 million
Conclusion
When it comes to accounting for stranded assets, it’s important to ensure guidelines are followed based on the type of accounting standards businesses must follow.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Drafting a will is not something that people, for the most part, want to think about. But no one gets out of life alive. So, if you want to have a say in what happens to your property and assets after you’re gone, a will is a very smart idea. Here are a few specific reasons why having a will makes good sense.
Facilitates Probate
First, a definition: Probate is the legal procedure your estate goes through after you pass. During this process, a court will start the process of distributing your estate to those you designate. When you have a will, the probate process has a legal document as a guide, one the court uses that clearly defines your wishes. This way, there are fewer roadblocks. Things go a lot more smoothly.
Protects Your Estate
Now, if you don’t have a will, there’s no binding legal document that espouses what you want to do with your assets. Instead, the probate court will distribute your estate according to your state’s intestacy laws. There’s no guarantee that the state agrees with what you want.
Designates Who Gets What
This is one of the most important. If your family includes ex-spouses and/or estranged relatives, having a will helps prevent squabbles. An unhappy relative will think twice about protesting when you have a well-drafted will.
Disinherits People, Too
If you don’t have a will, again, probate courts will distribute your estate based on your state’s intestacy laws, which create a hierarchy of inheritance among your surviving family members. Because families – and life – can be messy, when you have a will, you can specify who doesn’t get parts of your estate. Better still, you can even specify certain people to receive your assets as beneficiaries, who aren’t necessarily relatives. When you’re this specific within a legal document, it can further safeguard your wishes.
Provides For Your Children and Pets
When you have a will, it gives you the power to decide who will care for your children if they’re minors when you pass. If you don’t decide, a court will appoint a guardian. It’s safe to say that most people don’t want this; you know your children best. Since pets are considered property and they can’t inherit, you can make sure your beloved furry family members are adopted by a person or organization that you know and trust.
Specifies the Executor and Administrator of Your Estate
You get to decide who these people are, though sometimes they can be the same person. Generally, their function is to make sure your beneficiaries receive the assets you’ve designated for them. Having these trusted people in place will give you peace of mind. When you don’t have these individuals in place, you give up the control you could have had.
Helps Minimize Estate Taxes
Yes, it’s true. Your family, should they inherit property from you after you’re gone, might have to pay taxes on it. That’s why it pays to look into estate planning tools. When you have a will, you can build these stipulations into it. Just ask your accountant and/or lawyer to help you navigate these waters. It’s well worth it.
These are just a few of the reasons you need a will. Probably the main reason is that tomorrow isn’t guaranteed. When you’re gone, you’ve missed your opportunity to legally draft your final desires. That’s why, when you’ve set up provisions for all the things you’ve worked so hard for and all the people you leave behind, it’s truly an act of love.
Sources
Top 10 Reasons to Have a Will (findlaw.com)
Executor vs. Administrator: What’s the Difference? – Policygenius
Probate – What Is Probate & How To Avoid It | Trust & Will (trustandwill.com)
7 Reasons You Need a Will
September 1, 2024 · Blog, Tip of the Month, Uncategorized
⏱ 4 min read
Drafting a will is not something that people, for the most part, want to think about. But no one gets out of life alive. So, if you want to have a say in what happens to your property and assets after you’re gone, a will is a very smart idea. Here are a few specific reasons why having a will makes good sense.
Facilitates Probate
First, a definition: Probate is the legal procedure your estate goes through after you pass. During this process, a court will start the process of distributing your estate to those you designate. When you have a will, the probate process has a legal document as a guide, one the court uses that clearly defines your wishes. This way, there are fewer roadblocks. Things go a lot more smoothly.
Protects Your Estate
Now, if you don’t have a will, there’s no binding legal document that espouses what you want to do with your assets. Instead, the probate court will distribute your estate according to your state’s intestacy laws. There’s no guarantee that the state agrees with what you want.
Designates Who Gets What
This is one of the most important. If your family includes ex-spouses and/or estranged relatives, having a will helps prevent squabbles. An unhappy relative will think twice about protesting when you have a well-drafted will.
Disinherits People, Too
If you don’t have a will, again, probate courts will distribute your estate based on your state’s intestacy laws, which create a hierarchy of inheritance among your surviving family members. Because families – and life – can be messy, when you have a will, you can specify who doesn’t get parts of your estate. Better still, you can even specify certain people to receive your assets as beneficiaries, who aren’t necessarily relatives. When you’re this specific within a legal document, it can further safeguard your wishes.
Provides For Your Children and Pets
When you have a will, it gives you the power to decide who will care for your children if they’re minors when you pass. If you don’t decide, a court will appoint a guardian. It’s safe to say that most people don’t want this; you know your children best. Since pets are considered property and they can’t inherit, you can make sure your beloved furry family members are adopted by a person or organization that you know and trust.
Specifies the Executor and Administrator of Your Estate
You get to decide who these people are, though sometimes they can be the same person. Generally, their function is to make sure your beneficiaries receive the assets you’ve designated for them. Having these trusted people in place will give you peace of mind. When you don’t have these individuals in place, you give up the control you could have had.
Helps Minimize Estate Taxes
Yes, it’s true. Your family, should they inherit property from you after you’re gone, might have to pay taxes on it. That’s why it pays to look into estate planning tools. When you have a will, you can build these stipulations into it. Just ask your accountant and/or lawyer to help you navigate these waters. It’s well worth it.
These are just a few of the reasons you need a will. Probably the main reason is that tomorrow isn’t guaranteed. When you’re gone, you’ve missed your opportunity to legally draft your final desires. That’s why, when you’ve set up provisions for all the things you’ve worked so hard for and all the people you leave behind, it’s truly an act of love.
Sources
Top 10 Reasons to Have a Will (findlaw.com)
Executor vs. Administrator: What’s the Difference? – Policygenius
Probate – What Is Probate & How To Avoid It | Trust & Will (trustandwill.com)
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
On Jan. 1, 2024, the U.S. government debuted the Corporate Transparency Act (CTA). This legislation established the requirement for the majority of private companies, both big and small, to file information with the Financial Crimes Enforcement Network (FinCEN).
As with most new laws, the initial guidance and interpretations have been both challenged and questioned. In response, FinCEN recently turned out new FAQs, which we review below.
Big Question First: To Report or Not
Reporting is generally required by all private, for-profit entities. This includes corporations, LLCs, S-Corps, etc., whenever the company was created by filing a document with the office of the Secretary of State. Entities formed under the laws of jurisdictions outside the United States are also likely subject to reporting if they are registered to do business in the United States.
To help visualize the above, you can take a look at this flowchart published on the FinCEN website.
Screenshot from FinCEN website
While the general rules seem (and are) broad in construction, there are 23 specific exemptions, including publicly traded companies, nonprofits, and certain large operating companies. The FinCEN’s Small Entity Compliance Guide checklist can help in determining if you fall under an exemption.
Now, let’s move on to more specific questions.
Who is a beneficial owner?
An individual who either directly or indirectly exercises substantial controls or owns 25 percent or more of the reporting company.
What constitutes substantial control?
There are four (separate) ways to exercise substantial control:
The individual is a senior officer
Has the authority to appoint or remove officers or a majority of directors
An important decision-maker (regarding strategic, business, or finance)
They have any other form of substantial control as per the FinCEN’s Small Entity Compliance Guide.
Who is a company applicant for a reporting company?
Another of the more perplexing questions revolves around exactly who a company applicant of a reporting company is.
First, only reporting companies created or registered on or after Jan. 1, 2024, need to concern themselves with the company applicant rules; companies formed before are exempt.
There are two possible individuals who could be considered company applicants. One is the person who directly files the documents to create and register the company. This person will always exist and be an applicant of the reporting company. In the case where there were multiple people involved in the filing or registration, the individual who primarily controlled the filing is also considered an applicant.
Thankfully, FinCEN created another handy flowchart to help navigate through this rather confusing decision.
Screenshot from FinCEN website
What about sole proprietorships?
It depends. Sole proprietorships only have to report if the entity was created by filing a document with a secretary of state or similar office. In other words, if you just start freelancing and don’t file anything with a secretary of state office, you are not subject to the reporting requirements. Basically, if you didn’t form an LLC, you don’t need to report. For example, obtaining an employer identification number, a fictitious business name, or a professional or occupational license does not subject you to the FinCEN reporting requirements.
What if my company ceased to exist before the CTA requirements went into effect?
If a company ceased to exist on or before Jan. 1, 2024, then they are NOT subject to the reporting requirements.
Do I have to report more than once?
No, you only have to file an initial report once. There is NOT an annual report. You do, however, need to amend your original filing to update pertinent changes or corrections within 30 days of their occurrence.
What happens if I don’t file a report?
Willful violation can subject one to a fine of up to $500 per day until the violation is resolved. Criminal penalties could also be imposed, resulting in up to two years imprisonment and a fine of up to $10,000.
Conclusion
The FinCEN released its guidance to clarify uncertainties around the new CTA-created reporting requirements. The goal is to ensure full and accurate compliance without undue burden on companies and individuals.
Important Update on New Company Reporting Laws CTA – BOI
September 1, 2024 · Blog, Tax and Financial News, Uncategorized
⏱ 4 min read
On Jan. 1, 2024, the U.S. government debuted the Corporate Transparency Act (CTA). This legislation established the requirement for the majority of private companies, both big and small, to file information with the Financial Crimes Enforcement Network (FinCEN).
As with most new laws, the initial guidance and interpretations have been both challenged and questioned. In response, FinCEN recently turned out new FAQs, which we review below.
Big Question First: To Report or Not
Reporting is generally required by all private, for-profit entities. This includes corporations, LLCs, S-Corps, etc., whenever the company was created by filing a document with the office of the Secretary of State. Entities formed under the laws of jurisdictions outside the United States are also likely subject to reporting if they are registered to do business in the United States.
To help visualize the above, you can take a look at this flowchart published on the FinCEN website.
Screenshot from FinCEN website
While the general rules seem (and are) broad in construction, there are 23 specific exemptions, including publicly traded companies, nonprofits, and certain large operating companies. The FinCEN’s Small Entity Compliance Guide checklist can help in determining if you fall under an exemption.
Now, let’s move on to more specific questions.
Who is a beneficial owner?
An individual who either directly or indirectly exercises substantial controls or owns 25 percent or more of the reporting company.
What constitutes substantial control?
There are four (separate) ways to exercise substantial control:
The individual is a senior officer
Has the authority to appoint or remove officers or a majority of directors
An important decision-maker (regarding strategic, business, or finance)
They have any other form of substantial control as per the FinCEN’s Small Entity Compliance Guide.
Who is a company applicant for a reporting company?
Another of the more perplexing questions revolves around exactly who a company applicant of a reporting company is.
First, only reporting companies created or registered on or after Jan. 1, 2024, need to concern themselves with the company applicant rules; companies formed before are exempt.
There are two possible individuals who could be considered company applicants. One is the person who directly files the documents to create and register the company. This person will always exist and be an applicant of the reporting company. In the case where there were multiple people involved in the filing or registration, the individual who primarily controlled the filing is also considered an applicant.
Thankfully, FinCEN created another handy flowchart to help navigate through this rather confusing decision.
Screenshot from FinCEN website
What about sole proprietorships?
It depends. Sole proprietorships only have to report if the entity was created by filing a document with a secretary of state or similar office. In other words, if you just start freelancing and don’t file anything with a secretary of state office, you are not subject to the reporting requirements. Basically, if you didn’t form an LLC, you don’t need to report. For example, obtaining an employer identification number, a fictitious business name, or a professional or occupational license does not subject you to the FinCEN reporting requirements.
What if my company ceased to exist before the CTA requirements went into effect?
If a company ceased to exist on or before Jan. 1, 2024, then they are NOT subject to the reporting requirements.
Do I have to report more than once?
No, you only have to file an initial report once. There is NOT an annual report. You do, however, need to amend your original filing to update pertinent changes or corrections within 30 days of their occurrence.
What happens if I don’t file a report?
Willful violation can subject one to a fine of up to $500 per day until the violation is resolved. Criminal penalties could also be imposed, resulting in up to two years imprisonment and a fine of up to $10,000.
Conclusion
The FinCEN released its guidance to clarify uncertainties around the new CTA-created reporting requirements. The goal is to ensure full and accurate compliance without undue burden on companies and individuals.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
 Continuing Appropriations and Extensions Act, 2025 (HR 9747) – This continuing resolution was introduced on Sept. 22 as a “clean” extenuation of the federal budget to fund the government until Dec. 20. Up until this point, a handful of Republicans had attached unrelated bills pertaining to November election restrictions, which they did not have the votes to pass in the House and would never have passed in the Senate. After several weeks of threatening to shut down the government by not passing a continuing appropriations bill, the House Speaker proposed this “last-minute” tied over with the minimum appropriations necessary to keep the government up and running. While it still does not solidify the federal budget for the 2025 fiscal year (Sept. 29, 2024, through Sept. 27, 2025), this bill is expected to pass in the House on Sept. 25 and to clear the Senate and be signed by the president by Sept. 29.



 Step 5: Estate Plan
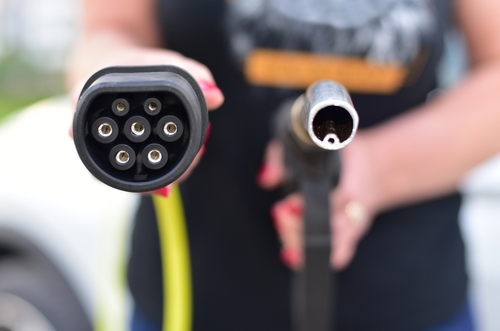 With more than 14 million electric vehicle (EV) registrations in 2023 worldwide and 2023 seeing an increase in EV sales over 2022 by 35 percent, manufacturers are probably happy – but not those producing the traditional internal combustion engine (ICE) vehicles. This is according to the International Energy Agency’s Global EV Outlook 2024: Trends in Electric Cars.
 Drafting a will is not something that people, for the most part, want to think about. But no one gets out of life alive. So, if you want to have a say in what happens to your property and assets after you’re gone, a will is a very smart idea. Here are a few specific reasons why having a will makes good sense.
 On Jan. 1, 2024, the U.S. government debuted the Corporate Transparency Act (CTA). This legislation established the requirement for the majority of private companies, both big and small, to file information with the Financial Crimes Enforcement Network (FinCEN).

