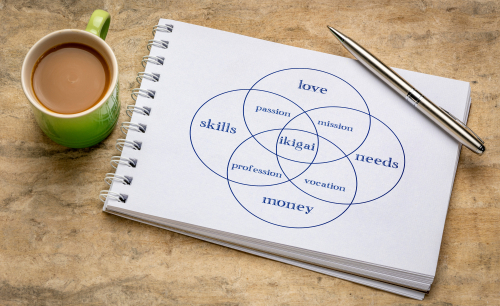
What do you consider to be your purpose in this world? Few people think about their life that way. In Japan, they call it your ikigai. In France, they refer to your raison d’etre. For Americans, that roughly translates to your purpose in life or your reason for being.
It’s easy to consider your family or even your career as your reason to live. But true embracement of the ikigai concept is more of a lifestyle, not a specific person, place or thing.
Your purpose may not even be something you’ve pursued in your adult life. Many of us follow the socially expected path: higher education, a good job, a rewarding career, marriage, home, and family. But those things are not everyone’s raison d’etre. They might wake up one morning thinking that once they’ve achieved all those goals, they will finally get the chance to do the one they’ve always wanted. What is that?
The older we get, the more we lose a spouse or life partner, siblings, or children – and those who retire no longer have work to feel fulfilled. As part of your retirement planning effort, consider life without any of those things. How would you bear it? If you outlive your career and loved ones, what would you do?
Note that your ikigai does not insulate you from bad things happening. Instead, it’s the thing you look forward to when the smoke clears: the light at the end of the tunnel. On balance, it’s the thing that helps get you through the pain and restores happiness. In fact, discovering your raison d’etre can help you better cope with stress and loss. People who pursue their ikigai tend to have better mental health, experience fewer chronic diseases, and are more likely to live longer.
Oftentimes ikigai is felt as part of a process. For example, the joy of mixing ingredients to prepare baked goods or a meal. Planting a garden. Rebuilding an engine. It can be the process of writing or painting or playing an instrument, but not necessarily finishing a novel or singing in public. It can be as simple as finding joy in daily activities, nurturing relationships or doing community service.
Another advantage to ikigai is that it can connect you with other people who share your passion, which can be very important as you grow older and more isolated. By leaning into your ikigai, you could expand your social network with connections that are meaningful and fulfilling.
For some people, their raison d’etre is spiritual. A belief and perhaps a greater connection to a higher being. They may wish to spend more time becoming involved in church activities, reading scripture that supports their religion, or even exploring other religions.
The Japanese culture believes that each individual has an inherent ikigai based on their personal values and beliefs. One way to think about it is as your philosophy on life. Since this step is a part of retirement planning, it is fortunate that you have lived long enough to have developed some philosophies on life.
For example, some people discover that family does not just consist of blood relatives. Instead, their concept of family is people who are there through good and bad times, who always show love and respect, who you can rely on. Those things might not always be true among family members who meet the traditional definition. This type of ikigai may help you recognize that the death of loved ones does not necessarily mean you lose your family. You can always build and add to your family (e.g., neighbors and friends, fostering children or pets, big brother/big sister programs).
How Do You Find Your Ikigai??
Many times, the hustle and bustle of life keeps us from finding our true purpose. We proceed as loyal soldiers down a path prescribed by society instead of pursuing things that may bring us greater happiness. There’s nothing wrong with a career and family, but there is likely something more that each of us can pursue that is personal and soul-enriching. Sometimes, you can discover your raison d’etre by exploring your passions, values, strengths, and skills. For example, ask yourself the following questions:
When I was a child, I loved doing…
If money didn’t matter, I would be…
If I believed I could not fail, I would…
I completely lose track of time when I am…
I am most happy with who I am when I…
I am really good at…
If I didn’t care what others thought, I would…
In my free time, I love to…
If I had only six months to live, I would spend my time…
If I were to die tomorrow, I would regret that I did not…
Consider hobbies or classes that you’ve always wanted to try or past experiences or achievements that gave you a sense of satisfaction and fulfillment. Recall where you have found inspiration in the past, and pinpoint what lies at the cross-section of doing what you love and doing what you’re good at.
Remember that your reason for living is more of a journey, not a destination. Finding your ikigai may take a lifetime to discover, so don’t be afraid to try out different pursuits. In fact, your reason for being may simply be to try new things.
Pre-Retirement Planning Guide – Finding Purpose In Life
December 1, 2024 · Blog, Financial Planning
⏱ 5 min read
Step 7: Find Your Raison d’Etre
What do you consider to be your purpose in this world? Few people think about their life that way. In Japan, they call it your ikigai. In France, they refer to your raison d’etre. For Americans, that roughly translates to your purpose in life or your reason for being.
It’s easy to consider your family or even your career as your reason to live. But true embracement of the ikigai concept is more of a lifestyle, not a specific person, place or thing.
Your purpose may not even be something you’ve pursued in your adult life. Many of us follow the socially expected path: higher education, a good job, a rewarding career, marriage, home, and family. But those things are not everyone’s raison d’etre. They might wake up one morning thinking that once they’ve achieved all those goals, they will finally get the chance to do the one they’ve always wanted. What is that?
The older we get, the more we lose a spouse or life partner, siblings, or children – and those who retire no longer have work to feel fulfilled. As part of your retirement planning effort, consider life without any of those things. How would you bear it? If you outlive your career and loved ones, what would you do?
Note that your ikigai does not insulate you from bad things happening. Instead, it’s the thing you look forward to when the smoke clears: the light at the end of the tunnel. On balance, it’s the thing that helps get you through the pain and restores happiness. In fact, discovering your raison d’etre can help you better cope with stress and loss. People who pursue their ikigai tend to have better mental health, experience fewer chronic diseases, and are more likely to live longer.
Oftentimes ikigai is felt as part of a process. For example, the joy of mixing ingredients to prepare baked goods or a meal. Planting a garden. Rebuilding an engine. It can be the process of writing or painting or playing an instrument, but not necessarily finishing a novel or singing in public. It can be as simple as finding joy in daily activities, nurturing relationships or doing community service.
Another advantage to ikigai is that it can connect you with other people who share your passion, which can be very important as you grow older and more isolated. By leaning into your ikigai, you could expand your social network with connections that are meaningful and fulfilling.
For some people, their raison d’etre is spiritual. A belief and perhaps a greater connection to a higher being. They may wish to spend more time becoming involved in church activities, reading scripture that supports their religion, or even exploring other religions.
The Japanese culture believes that each individual has an inherent ikigai based on their personal values and beliefs. One way to think about it is as your philosophy on life. Since this step is a part of retirement planning, it is fortunate that you have lived long enough to have developed some philosophies on life.
For example, some people discover that family does not just consist of blood relatives. Instead, their concept of family is people who are there through good and bad times, who always show love and respect, who you can rely on. Those things might not always be true among family members who meet the traditional definition. This type of ikigai may help you recognize that the death of loved ones does not necessarily mean you lose your family. You can always build and add to your family (e.g., neighbors and friends, fostering children or pets, big brother/big sister programs).
How Do You Find Your Ikigai??
Many times, the hustle and bustle of life keeps us from finding our true purpose. We proceed as loyal soldiers down a path prescribed by society instead of pursuing things that may bring us greater happiness. There’s nothing wrong with a career and family, but there is likely something more that each of us can pursue that is personal and soul-enriching. Sometimes, you can discover your raison d’etre by exploring your passions, values, strengths, and skills. For example, ask yourself the following questions:
When I was a child, I loved doing…
If money didn’t matter, I would be…
If I believed I could not fail, I would…
I completely lose track of time when I am…
I am most happy with who I am when I…
I am really good at…
If I didn’t care what others thought, I would…
In my free time, I love to…
If I had only six months to live, I would spend my time…
If I were to die tomorrow, I would regret that I did not…
Consider hobbies or classes that you’ve always wanted to try or past experiences or achievements that gave you a sense of satisfaction and fulfillment. Recall where you have found inspiration in the past, and pinpoint what lies at the cross-section of doing what you love and doing what you’re good at.
Remember that your reason for living is more of a journey, not a destination. Finding your ikigai may take a lifetime to discover, so don’t be afraid to try out different pursuits. In fact, your reason for being may simply be to try new things.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Yep, it’s the end of another year! Chances are, you didn’t keep every resolution you made last year, for example, those goals about working out. (No shame here; we all do this!) However, the good news is that your fiscal goals can be a bit easier to achieve. Here are a few financial resolutions that are no-brainers, simple, and, best of all, no sweat.
Get a snapshot of your net worth. This is critical. Sit down and calculate this. When you know how much you have in terms of assets and liabilities, you can more easily determine where you need to make changes to your budget. For instance, this might be spending less on dining out and stocking more away in savings and investments. Understanding how much you have to work with is the first step to reaching your goals.
Pay off credit cards. This might well be an ongoing task, but the end of the year is a great time to take a breath, make a plan, and hit the ground running in the new year. If you have high-interest cards, look for limited-time, lower-interest and/or zero-interest cards. Some lenders will even give you as long as 21 months without interest. If you find yourself using credit cards more than you like, another way to get a handle on this is to use cash when you’re out at stores and restaurants. Seeing the dollars actually leaving your hands as opposed to just swiping your plastic might give you a needed dose of reality.
Update your savings goals. If you want to easily increase your savings, choose an amount and have it auto-drafted from your paycheck or checking account into your savings every month. This way, you’ll learn to live on the amount you have left. When you never see the amount you’re tucking away, you won’t miss it.
Review and reset your investments. Take some time to pull together all your assets: IRAs, retirement accounts, and employer 401(k) plans. If you can contribute more to any of these, all the better. For 401(k)s, the IRS just announced a cost-of-living adjustment for retirement plans and IRAs – the 401(k) contribution limit for 2025 is $23,500, up from $23,000 in 2024. However, individual retirement account (IRA) contributions will continue to be $7,000 in 2025, the same as in 2024. If you’re over 50, here’s some good news: You’ll be able to make even larger catch-up contributions than other workers because of a provision in Secure 2.0, a federal retirement law. Beginning in 2025, employees aged 60, 61, 62, or 63 who participate in workplace retirement plans can make catch-up contributions of up to $11,250.
Take a look at your credit report. This is key. You’re entitled to one free credit report a year from each of the three credit agencies, so doing this is easy peasy. Pull up your report and give it a look-see. If you see anything negative, take action to repair it. If there are any errors, correct them asap. To get started, go to AnnualCreditReport.com.
While there are many other money-related resolutions you can make, starting with ones that take minimal effort while yielding maximum results is a good place to begin, not to mention, a great way ease into the new year.
5 New Year’s Financial Resolutions You Can Actually Keep
December 1, 2024 · Blog, Tip of the Month, Uncategorized
⏱ 3 min read
Yep, it’s the end of another year! Chances are, you didn’t keep every resolution you made last year, for example, those goals about working out. (No shame here; we all do this!) However, the good news is that your fiscal goals can be a bit easier to achieve. Here are a few financial resolutions that are no-brainers, simple, and, best of all, no sweat.
Get a snapshot of your net worth. This is critical. Sit down and calculate this. When you know how much you have in terms of assets and liabilities, you can more easily determine where you need to make changes to your budget. For instance, this might be spending less on dining out and stocking more away in savings and investments. Understanding how much you have to work with is the first step to reaching your goals.
Pay off credit cards. This might well be an ongoing task, but the end of the year is a great time to take a breath, make a plan, and hit the ground running in the new year. If you have high-interest cards, look for limited-time, lower-interest and/or zero-interest cards. Some lenders will even give you as long as 21 months without interest. If you find yourself using credit cards more than you like, another way to get a handle on this is to use cash when you’re out at stores and restaurants. Seeing the dollars actually leaving your hands as opposed to just swiping your plastic might give you a needed dose of reality.
Update your savings goals. If you want to easily increase your savings, choose an amount and have it auto-drafted from your paycheck or checking account into your savings every month. This way, you’ll learn to live on the amount you have left. When you never see the amount you’re tucking away, you won’t miss it.
Review and reset your investments. Take some time to pull together all your assets: IRAs, retirement accounts, and employer 401(k) plans. If you can contribute more to any of these, all the better. For 401(k)s, the IRS just announced a cost-of-living adjustment for retirement plans and IRAs – the 401(k) contribution limit for 2025 is $23,500, up from $23,000 in 2024. However, individual retirement account (IRA) contributions will continue to be $7,000 in 2025, the same as in 2024. If you’re over 50, here’s some good news: You’ll be able to make even larger catch-up contributions than other workers because of a provision in Secure 2.0, a federal retirement law. Beginning in 2025, employees aged 60, 61, 62, or 63 who participate in workplace retirement plans can make catch-up contributions of up to $11,250.
Take a look at your credit report. This is key. You’re entitled to one free credit report a year from each of the three credit agencies, so doing this is easy peasy. Pull up your report and give it a look-see. If you see anything negative, take action to repair it. If there are any errors, correct them asap. To get started, go to AnnualCreditReport.com.
While there are many other money-related resolutions you can make, starting with ones that take minimal effort while yielding maximum results is a good place to begin, not to mention, a great way ease into the new year.
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
According to estimates, inflation adjustments to the Internal Revenue Code are expected to yield increases of 2.8 percent compared to 2024 amounts. This means wider tax brackets and increased exemptions, among other things. With the U.S. Bureau of Labor Statistics consumer price index (CPI) moderating, this increase is about 50 percent less than 2024’s inflation adjustment. Below, we’ll look at what the projected 2025 inflation adjustment means in terms of dollars and cents for you and your taxes.
Individual Income Tax Brackets
The tables below illustrate the individual income tax rates and brackets for 2025.
Individual Income Tax Brackets & Rates: Tax Year 2025
Single Taxpayers
10%
0 – $11,925
12%
$11,926 – $48,475
22%
$48,476 – $103,350
24%
$103,351 – $197,300
32%
$197,301 – $250,525
35%
$250,526 – $626,350
37%
$626,351 and Over
Married Filing Jointly
10%
0 – $23,850
12%
$23,851 – $96,950
22%
$96,951 – $206,700
24%
$206,701 – $394,600
32%
$394,601 – $501,050
35%
$501,051 – $751,600
37%
$751,601 and Over
Married Filing Separately
10%
0 – $11,925
12%
$11,926 – $48,475
22%
$48,476 – $103,350
24%
$103,351 – $197,300
32%
$197,301 – $250,525
35%
$250,526 – $375,800
37%
$375,801 and Over
Heads of Household
10%
0 – $17,000
12%
$17,001- $64,850
22%
$64,851 – $103,350
24%
$103,351 – $197,300
32%
$197,301 – $250,500
35%
$250,501 – $626,350
37%
$626,351 and Over
Trusts & Estates Tax Brackets
The table below illustrates what the income rates and brackets are expected to look like for Trusts and Estates in 2025.
Projected Trusts and Estates Tax Brackets & Rates: Tax Year 2025
10%
0 – $3,150
24%
$3,151- $11,450
35%
$11,451 – $15,650
37%
$15,651 and Over
Standard Deduction Amounts
The table below illustrates what the projected standard deduction amounts will be for 2025, with a comparison to 2024.
Projected Standard Deduction Amounts
2024
2025
Single
$14,600
$15,750
Married Filing Jointly
$29,200
$31,500
Married Filing Separately
$14,600
$15,750
Head of Household
$21,900
$23,625
Alternative Minimum Tax (AMT)
The table below illustrates the anticipated AMT exemptions for 2025.
AMT Exemption Amounts Tax Year 2025
Single
$88,100
Married Filing Jointly
$137,000
Married Filing Separately
$68,500
Trust & Estates
$30,700
Capital Gains
The rates applied to long-term capital gains are not expected to change for 2025; however, the brackets that apply to different rates will expand. Note that, in considering the table below, a 20 percent tax rate applies to capital gains that are over the 37 percent ordinary tax rate threshold. Furthermore, capital gains on art and collectibles are subject to other exceptions.
Maximum Capital Gains Rates for 2025
Zero Rate
15% Rate
Single
$48,350
$533,400
Married Filing Jointly
$96,700
$600,050
Married Filing Separately
$48,350
$300,000
Head of Household
$64,750
$566,700
Trusts & Estates
$3,250
$15,900
Conclusion
First, it’s important to remember that all the figures above are only projections. The IRS will not publish the official numbers until later this year. Moreover, as these rates and brackets have increased, they have done so significantly less than in 2024 and 2023, largely driven by lower inflation.
2025 Federal Income Tax Brackets
November 1, 2024 · Blog, Tax and Financial News, Uncategorized
⏱ 2 min read
According to estimates, inflation adjustments to the Internal Revenue Code are expected to yield increases of 2.8 percent compared to 2024 amounts. This means wider tax brackets and increased exemptions, among other things. With the U.S. Bureau of Labor Statistics consumer price index (CPI) moderating, this increase is about 50 percent less than 2024’s inflation adjustment. Below, we’ll look at what the projected 2025 inflation adjustment means in terms of dollars and cents for you and your taxes.
Individual Income Tax Brackets
The tables below illustrate the individual income tax rates and brackets for 2025.
Individual Income Tax Brackets & Rates: Tax Year 2025
Single Taxpayers
10%
0 – $11,925
12%
$11,926 – $48,475
22%
$48,476 – $103,350
24%
$103,351 – $197,300
32%
$197,301 – $250,525
35%
$250,526 – $626,350
37%
$626,351 and Over
Married Filing Jointly
10%
0 – $23,850
12%
$23,851 – $96,950
22%
$96,951 – $206,700
24%
$206,701 – $394,600
32%
$394,601 – $501,050
35%
$501,051 – $751,600
37%
$751,601 and Over
Married Filing Separately
10%
0 – $11,925
12%
$11,926 – $48,475
22%
$48,476 – $103,350
24%
$103,351 – $197,300
32%
$197,301 – $250,525
35%
$250,526 – $375,800
37%
$375,801 and Over
Heads of Household
10%
0 – $17,000
12%
$17,001- $64,850
22%
$64,851 – $103,350
24%
$103,351 – $197,300
32%
$197,301 – $250,500
35%
$250,501 – $626,350
37%
$626,351 and Over
Trusts & Estates Tax Brackets
The table below illustrates what the income rates and brackets are expected to look like for Trusts and Estates in 2025.
Projected Trusts and Estates Tax Brackets & Rates: Tax Year 2025
10%
0 – $3,150
24%
$3,151- $11,450
35%
$11,451 – $15,650
37%
$15,651 and Over
Standard Deduction Amounts
The table below illustrates what the projected standard deduction amounts will be for 2025, with a comparison to 2024.
Projected Standard Deduction Amounts
2024
2025
Single
$14,600
$15,750
Married Filing Jointly
$29,200
$31,500
Married Filing Separately
$14,600
$15,750
Head of Household
$21,900
$23,625
Alternative Minimum Tax (AMT)
The table below illustrates the anticipated AMT exemptions for 2025.
AMT Exemption Amounts Tax Year 2025
Single
$88,100
Married Filing Jointly
$137,000
Married Filing Separately
$68,500
Trust & Estates
$30,700
Capital Gains
The rates applied to long-term capital gains are not expected to change for 2025; however, the brackets that apply to different rates will expand. Note that, in considering the table below, a 20 percent tax rate applies to capital gains that are over the 37 percent ordinary tax rate threshold. Furthermore, capital gains on art and collectibles are subject to other exceptions.
Maximum Capital Gains Rates for 2025
Zero Rate
15% Rate
Single
$48,350
$533,400
Married Filing Jointly
$96,700
$600,050
Married Filing Separately
$48,350
$300,000
Head of Household
$64,750
$566,700
Trusts & Estates
$3,250
$15,900
Conclusion
First, it’s important to remember that all the figures above are only projections. The IRS will not publish the official numbers until later this year. Moreover, as these rates and brackets have increased, they have done so significantly less than in 2024 and 2023, largely driven by lower inflation.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
This metric, which is also referred to as the cash cycle or the net operating cycle, looks at the time a business takes to recover its investment in inventory to eventually sell. The process starts from selling its goods, collecting on outstanding receivables or invoices, and satisfying its operating costs with the sale proceeds. It’s normally measured in days to determine the company’s financial health.
The less time necessary to complete the CCC, the healthier a company is financially because it means the business’ money spends less time tied up in inventory or collecting on outstanding inventory. It’s important to be mindful that different industries have different CCC time frames. Generally speaking, most calculations are done on either a quarterly (90 day) or an annual basis (365 days).
How to Calculate CCC
The formula is as follows:
(CCC) = Days Inventory Outstanding (DIO) + Days Sales Outstanding (DSO) − Days Payable Outstanding (DPO)
It can be broken down into three different stages:
Stage 1
Days Inventory Outstanding (DIO) looks at how many days the inventory takes to sell to customers. It’s calculated as follows:
DIO = (Average Inventory (AI) / COGS) x Time-Frame (In Days)
AI = 1/2 x (BI + FI)
BI = Beginning Inventory
FI = Final Inventory
It’s important to define COGS, taken from the Income Statement, which is Cost of Goods Sold or the costs personally connected to creation of goods or services (raw materials, labor or electricity). The lower the number, the faster a business is selling its goods.
Stage 2
Days Sales Outstanding (DSO) measures the time it takes the business to collect payment from all outstanding sales completed.
DSO = Average Accounts Receivable (AAR) / Daily Revenue
AAR = 1/2 x (SAR + FAR)
SAR = Starting AR
FAR = Final AR
Accounts Receivable are what companies record on their balance sheet to keep track of what customers owe for the goods delivered or services rendered. The lower the results, the better the company’s cash position is because they’re able to satisfy outstanding invoices.
Stage 3
Days Payable Outstanding (DPO) is the third and final stage that calculates how much businesses owe to their suppliers the business has sourced input materials from, within the time frame the suppliers’ invoices are due.
DPO = Average Accounts Payable (AAP) / Daily COGS
Where:
AAP = 0.5 x (SAP + FAP)
SAP = Starting AP
FAP = Final AP
COGS = Cost of Goods Sold
There are different ways to interpret the DPO result. A low DPO means the business is taking care of its bills from suppliers. However, potential investors, internal managers, and supervisors can see if the business can either negotiate lengthier payment terms while still maintaining good terms or if the company negotiates early payment terms or invests the money on a short-term basis to earn more for the company before paying suppliers’ bills. A high DPO, after an investigation of a company’s financials, might show the company is taking longer than its peers to pay creditors.
While calculating the CCC is relatively straightforward, the more complex process is interpreting it correctly and using judgment for a business based on industry averages and how the numbers relate to current economic conditions.
Cash Conversion Cycle (CCC) Defined
November 1, 2024 · Blog, General Business News, Uncategorized
⏱ 3 min read
This metric, which is also referred to as the cash cycle or the net operating cycle, looks at the time a business takes to recover its investment in inventory to eventually sell. The process starts from selling its goods, collecting on outstanding receivables or invoices, and satisfying its operating costs with the sale proceeds. It’s normally measured in days to determine the company’s financial health.
The less time necessary to complete the CCC, the healthier a company is financially because it means the business’ money spends less time tied up in inventory or collecting on outstanding inventory. It’s important to be mindful that different industries have different CCC time frames. Generally speaking, most calculations are done on either a quarterly (90 day) or an annual basis (365 days).
How to Calculate CCC
The formula is as follows:
(CCC) = Days Inventory Outstanding (DIO) + Days Sales Outstanding (DSO) − Days Payable Outstanding (DPO)
It can be broken down into three different stages:
Stage 1
Days Inventory Outstanding (DIO) looks at how many days the inventory takes to sell to customers. It’s calculated as follows:
DIO = (Average Inventory (AI) / COGS) x Time-Frame (In Days)
AI = 1/2 x (BI + FI)
BI = Beginning Inventory
FI = Final Inventory
It’s important to define COGS, taken from the Income Statement, which is Cost of Goods Sold or the costs personally connected to creation of goods or services (raw materials, labor or electricity). The lower the number, the faster a business is selling its goods.
Stage 2
Days Sales Outstanding (DSO) measures the time it takes the business to collect payment from all outstanding sales completed.
DSO = Average Accounts Receivable (AAR) / Daily Revenue
AAR = 1/2 x (SAR + FAR)
SAR = Starting AR
FAR = Final AR
Accounts Receivable are what companies record on their balance sheet to keep track of what customers owe for the goods delivered or services rendered. The lower the results, the better the company’s cash position is because they’re able to satisfy outstanding invoices.
Stage 3
Days Payable Outstanding (DPO) is the third and final stage that calculates how much businesses owe to their suppliers the business has sourced input materials from, within the time frame the suppliers’ invoices are due.
DPO = Average Accounts Payable (AAP) / Daily COGS
Where:
AAP = 0.5 x (SAP + FAP)
SAP = Starting AP
FAP = Final AP
COGS = Cost of Goods Sold
There are different ways to interpret the DPO result. A low DPO means the business is taking care of its bills from suppliers. However, potential investors, internal managers, and supervisors can see if the business can either negotiate lengthier payment terms while still maintaining good terms or if the company negotiates early payment terms or invests the money on a short-term basis to earn more for the company before paying suppliers’ bills. A high DPO, after an investigation of a company’s financials, might show the company is taking longer than its peers to pay creditors.
While calculating the CCC is relatively straightforward, the more complex process is interpreting it correctly and using judgment for a business based on industry averages and how the numbers relate to current economic conditions.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Social media has evolved from a simple networking platform to a powerful business tool. Businesses today use these platforms with billions of active users worldwide to connect with their target audience. Social media allows businesses of all sizes to reach audiences in a way that traditional advertising, such as print or television, cannot.
The Role of Social Media Marketing in Business Growth
Social media marketing uses social media platforms such as Facebook, LinkedIn, Instagram and TikTok to promote a business’ products or services. This is done through sharing content like posts, videos and ads to engage a targeted audience and eventually make sales.
With 5.22 billion social media users as of October 2024, businesses can reach customers around the world with ease. The platforms are also suitable for sharing information, enabling companies to communicate with customers about promotions, events or new products or services.
Each platform offers different strengths, and a business can choose which ones suit its target audience. For instance, LinkedIn is more professional and a good platform for B2B opportunities. On the other hand, TikTok and Instagram are suitable for visual storytelling, making them good places to showcase products.
Benefits of Social Media Marketing
Some of the key benefits of marketing on social media include the following:
Increased Brand Awareness Consistently and strategically posting on social media enhances brand visibility. A brand gains recognition as users engage with the content through likes, comments, and shares. Content that goes viral expands a business’ reach, introducing new audiences to the brand.
Improved Customer Engagement Social media gives businesses a direct line to customers. Whether replying to comments or through direct messages, these interactions help build trust and create a sense of loyalty. This two-way communication gives businesses a better understanding of customers’ needs while also allowing them to respond quickly to inquiries and feedback.
Cost-Effective Advertising Unlike traditional advertising, social media offers cost-effective marketing solutions. With social media, a business can run targeted ads based on demographics, interests or behaviors. This ensures they reach the right audience without wasting resources. This makes it possible for small businesses to leverage paid campaigns to increase their reach while staying within their budget.
Measurable Results and Analytics Social media marketing offers the ability to measure results through built-in analytic tools. A business can monitor follower growth, engagement rates, link clicks, and conversions. Such data-driven insights help businesses identify what is working, fine-tune their strategies, and continuously improve their campaigns.
Drive Website Traffic and Sales Sharing links to a business website on social media drives traffic to the site and increases conversions.
Social Media Strategies that Help in Business Growth
Content Marketing Creating engaging content is crucial in social media marketing. This involves using text, videos, images and infographics to capture the audience’s attention. One powerful tool in content marketing is storytelling – using emotional and relatable stories to connect with audiences will enhance loyalty and trust.
Influencer Marketing Influencers have huge followings, and their endorsements can significantly help a business. However, partnering with the right influencer is important to attract new customers and boost credibility.
Paid Ads and Promotions With paid ads, a business targets specific audiences in terms of location, age and interests. Social media also enables retargeting campaigns, which remind users about products they have previously viewed.
Community Building Social media allows a business to create a community for long-term relationships. This is done through creating groups or pages. These communities develop a sense of belonging, and customers are more likely to engage with the business over time and recommend it to others.
Challenges and How to Overcome Them
Staying Relevant in a Crowded Space Many businesses compete for customer attention, and standing out can be challenging. Therefore, businesses should keep up with social media trends, experiment with new formats and regularly update their strategies to align with changing consumer preferences.
Managing Negative Feedback Publicly Businesses may face criticism or negative feedback. Handling these situations professionally is crucial. It calls for prompt responses that show empathy and a willingness to resolve issues. This demonstrates accountability, which can turn a negative experience into an opportunity to build trust.
Creating Consistent Content Maintaining a steady flow of content can be overwhelming, especially for small businesses. Content calendars and automation tools can help plan posts in advance, ensuring consistent engagement without added stress. Repurposing existing content across platforms is another way to save time and effort.
Conclusion
Social media marketing has become a game-changer for businesses seeking growth in the digital age. It provides cost-effective ways to build brand awareness, engage with customers, and measure real-time success. However, success requires more than just presence – it demands strategic planning, creativity, and adaptability to overcome challenges and maintain relevance.
Social Media Marketing: A Game-Changer for Business Growth
November 1, 2024 · Blog, Uncategorized, What's New in Technology
⏱ 4 min read
Social media has evolved from a simple networking platform to a powerful business tool. Businesses today use these platforms with billions of active users worldwide to connect with their target audience. Social media allows businesses of all sizes to reach audiences in a way that traditional advertising, such as print or television, cannot.
The Role of Social Media Marketing in Business Growth
Social media marketing uses social media platforms such as Facebook, LinkedIn, Instagram and TikTok to promote a business’ products or services. This is done through sharing content like posts, videos and ads to engage a targeted audience and eventually make sales.
With 5.22 billion social media users as of October 2024, businesses can reach customers around the world with ease. The platforms are also suitable for sharing information, enabling companies to communicate with customers about promotions, events or new products or services.
Each platform offers different strengths, and a business can choose which ones suit its target audience. For instance, LinkedIn is more professional and a good platform for B2B opportunities. On the other hand, TikTok and Instagram are suitable for visual storytelling, making them good places to showcase products.
Benefits of Social Media Marketing
Some of the key benefits of marketing on social media include the following:
Increased Brand Awareness Consistently and strategically posting on social media enhances brand visibility. A brand gains recognition as users engage with the content through likes, comments, and shares. Content that goes viral expands a business’ reach, introducing new audiences to the brand.
Improved Customer Engagement Social media gives businesses a direct line to customers. Whether replying to comments or through direct messages, these interactions help build trust and create a sense of loyalty. This two-way communication gives businesses a better understanding of customers’ needs while also allowing them to respond quickly to inquiries and feedback.
Cost-Effective Advertising Unlike traditional advertising, social media offers cost-effective marketing solutions. With social media, a business can run targeted ads based on demographics, interests or behaviors. This ensures they reach the right audience without wasting resources. This makes it possible for small businesses to leverage paid campaigns to increase their reach while staying within their budget.
Measurable Results and Analytics Social media marketing offers the ability to measure results through built-in analytic tools. A business can monitor follower growth, engagement rates, link clicks, and conversions. Such data-driven insights help businesses identify what is working, fine-tune their strategies, and continuously improve their campaigns.
Drive Website Traffic and Sales Sharing links to a business website on social media drives traffic to the site and increases conversions.
Social Media Strategies that Help in Business Growth
Content Marketing Creating engaging content is crucial in social media marketing. This involves using text, videos, images and infographics to capture the audience’s attention. One powerful tool in content marketing is storytelling – using emotional and relatable stories to connect with audiences will enhance loyalty and trust.
Influencer Marketing Influencers have huge followings, and their endorsements can significantly help a business. However, partnering with the right influencer is important to attract new customers and boost credibility.
Paid Ads and Promotions With paid ads, a business targets specific audiences in terms of location, age and interests. Social media also enables retargeting campaigns, which remind users about products they have previously viewed.
Community Building Social media allows a business to create a community for long-term relationships. This is done through creating groups or pages. These communities develop a sense of belonging, and customers are more likely to engage with the business over time and recommend it to others.
Challenges and How to Overcome Them
Staying Relevant in a Crowded Space Many businesses compete for customer attention, and standing out can be challenging. Therefore, businesses should keep up with social media trends, experiment with new formats and regularly update their strategies to align with changing consumer preferences.
Managing Negative Feedback Publicly Businesses may face criticism or negative feedback. Handling these situations professionally is crucial. It calls for prompt responses that show empathy and a willingness to resolve issues. This demonstrates accountability, which can turn a negative experience into an opportunity to build trust.
Creating Consistent Content Maintaining a steady flow of content can be overwhelming, especially for small businesses. Content calendars and automation tools can help plan posts in advance, ensuring consistent engagement without added stress. Repurposing existing content across platforms is another way to save time and effort.
Conclusion
Social media marketing has become a game-changer for businesses seeking growth in the digital age. It provides cost-effective ways to build brand awareness, engage with customers, and measure real-time success. However, success requires more than just presence – it demands strategic planning, creativity, and adaptability to overcome challenges and maintain relevance.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
 Step 7: Find Your Raison d’Etre



 Yep, it’s the end of another year! Chances are, you didn’t keep every resolution you made last year, for example, those goals about working out. (No shame here; we all do this!) However, the good news is that your fiscal goals can be a bit easier to achieve. Here are a few financial resolutions that are no-brainers, simple, and, best of all, no sweat.
 According to estimates, inflation adjustments to the Internal Revenue Code are expected to yield increases of 2.8 percent compared to 2024 amounts. This means wider tax brackets and increased exemptions, among other things. With the U.S. Bureau of Labor Statistics consumer price index (CPI) moderating, this increase is about 50 percent less than 2024’s inflation adjustment. Below, we’ll look at what the projected 2025 inflation adjustment means in terms of dollars and cents for you and your taxes.
 This metric, which is also referred to as the cash cycle or the net operating cycle, looks at the time a business takes to recover its investment in inventory to eventually sell. The process starts from selling its goods, collecting on outstanding receivables or invoices, and satisfying its operating costs with the sale proceeds. It’s normally measured in days to determine the company’s financial health.
 Social media has evolved from a simple networking platform to a powerful business tool. Businesses today use these platforms with billions of active users worldwide to connect with their target audience. Social media allows businesses of all sizes to reach audiences in a way that traditional advertising, such as print or television, cannot.